2025中国医药研发创新与营销创新峰会
Overseas growth remained solid; domestic recovery should broaden in 2027E

Overseas growth remained solid; domestic recovery should broaden in 2027E

研报

Overseas growth remained solid; domestic recovery should broaden in 2027E

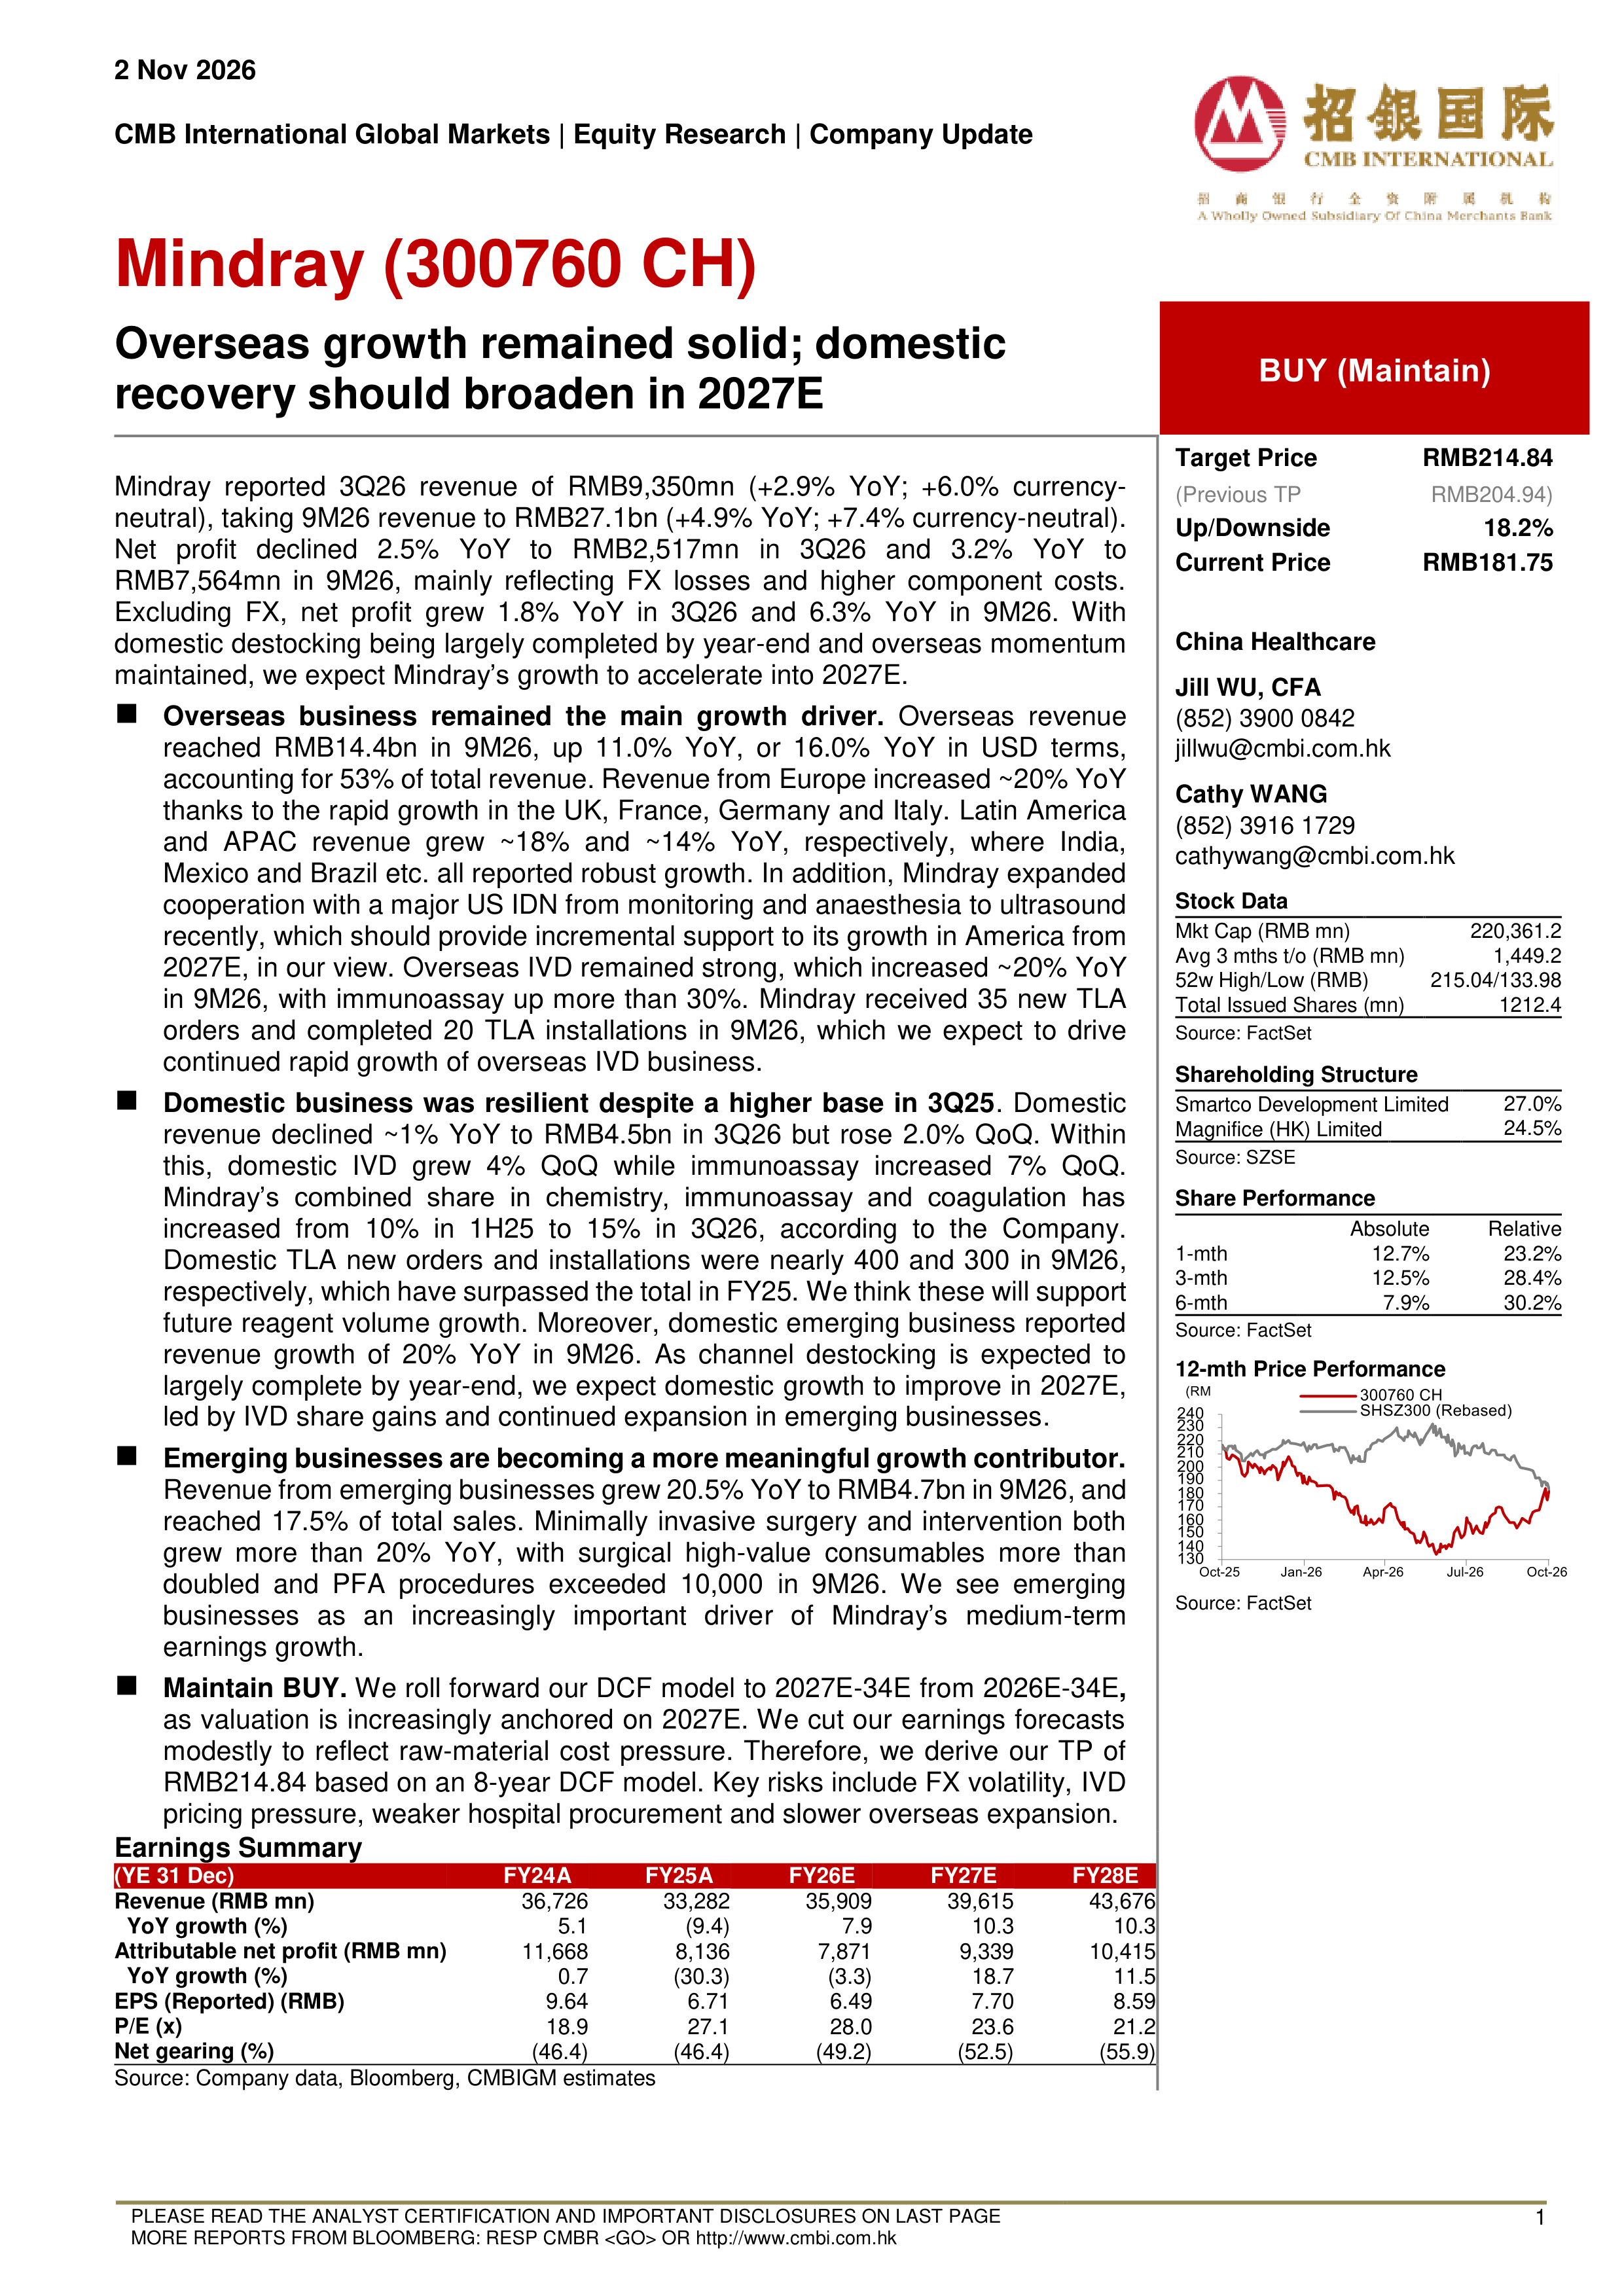
  迈瑞医疗(300760)   Mindray reported3Q26revenue of RMB9,350mn(+2.9%YoY;+6.0%currency-neutral),taking9M26revenue to RMB27.1bn(+4.9%YoY;+7.4%currency-neutral).Net profit declined2.5%YoY to RMB2,517mn in3Q26and3.2%YoY toRMB7,564mn in9M26,mainly reflecting FX losses and higher component costs.Excluding FX,net profit grew1.8%YoY in3Q26and6.3%YoY in9M26.Withdomestic destocking being largely completed by year-end and overseas momentummaintained,we expect Mindray’s growth to accelerate into2027E.   Overseas business remained the main growth driver.Overseas revenuereached RMB14.4bn in9M26,up11.0%YoY,or16.0%YoY in USD terms,accounting for53%of total revenue.Revenue from Europe increased~20%YoYthanks to the rapid growth in the UK,France,Germany and Italy.Latin Americaand APAC revenue grew~18%and~14%YoY,respectively,where India,Mexico and Brazil etc.all reported robust growth.In addition,Mindray expandedcooperation with a major US IDN from monitoring and anaesthesia to ultrasoundrecently,which should provide incremental support to its growth in America from2027E,in our view.Overseas IVD remained strong,which increased~20%YoYin9M26,with immunoassay up more than30%.Mindray received35new TLAorders and completed20TLA installations in9M26,which we expect to drivecontinued rapid growth of overseas IVD business.   Domestic business was resilient despite a higher base in3Q25.Domesticrevenue declined~1%YoY to RMB4.5bn in3Q26but rose2.0%QoQ.Withinthis,domestic IVD grew4%QoQ while immunoassay increased7%QoQ.Mindray’s combined share in chemistry,immunoassay and coagulation hasincreased from10%in1H25to15%in3Q26,according to the Company.Domestic TLA new orders and installations were nearly400and300in9M26,respectively,which have surpassed the total in FY25.We think these will supportfuture reagent volume growth.Moreover,domestic emerging business reportedrevenue growth of20%YoY in9M26.As channel destocking is expected tolargely complete by year-end,we expect domestic growth to improve in2027E,led by IVD share gains and continued expansion in emerging businesses.   Emerging businesses are becoming a more meaningful growth contributor.Revenue from emerging businesses grew20.5%YoY to RMB4.7bn in9M26,andreached17.5%of total sales.Minimally invasive surgery and intervention bothgrew more than20%YoY,with surgical high-value consumables more thandoubled and PFA procedures exceeded10,000in9M26.We see emergingbusinesses as an increasingly important driver of Mindray’s medium-termearnings growth.   Maintain BUY.We roll forward our DCF model to2027E-34E from2026E-34E,as valuation is increasingly anchored on2027E.We cut our earnings forecastsmodestly to reflect raw-material cost pressure.Therefore,we derive our TP ofRMB214.84based on an8-year DCF model.Key risks include FX volatility,IVDpricing pressure,weaker hospital procurement and slower overseas expansion.

报告标签:
  • 个股研报
报告专题:
  • 下载次数:

    2339 次

  • 发布机构:

    CMB International Capital Corporation Limited

  • 发布日期:

    2026-11-02

  • 页数:

    5页

下载全文
定制咨询
报告内容
报告摘要

  迈瑞医疗(300760)

  Mindray reported3Q26revenue of RMB9,350mn(+2.9%YoY;+6.0%currency-neutral),taking9M26revenue to RMB27.1bn(+4.9%YoY;+7.4%currency-neutral).Net profit declined2.5%YoY to RMB2,517mn in3Q26and3.2%YoY toRMB7,564mn in9M26,mainly reflecting FX losses and higher component costs.Excluding FX,net profit grew1.8%YoY in3Q26and6.3%YoY in9M26.Withdomestic destocking being largely completed by year-end and overseas momentummaintained,we expect Mindray’s growth to accelerate into2027E.

  Overseas business remained the main growth driver.Overseas revenuereached RMB14.4bn in9M26,up11.0%YoY,or16.0%YoY in USD terms,accounting for53%of total revenue.Revenue from Europe increased~20%YoYthanks to the rapid growth in the UK,France,Germany and Italy.Latin Americaand APAC revenue grew~18%and~14%YoY,respectively,where India,Mexico and Brazil etc.all reported robust growth.In addition,Mindray expandedcooperation with a major US IDN from monitoring and anaesthesia to ultrasoundrecently,which should provide incremental support to its growth in America from2027E,in our view.Overseas IVD remained strong,which increased~20%YoYin9M26,with immunoassay up more than30%.Mindray received35new TLAorders and completed20TLA installations in9M26,which we expect to drivecontinued rapid growth of overseas IVD business.

  Domestic business was resilient despite a higher base in3Q25.Domesticrevenue declined~1%YoY to RMB4.5bn in3Q26but rose2.0%QoQ.Withinthis,domestic IVD grew4%QoQ while immunoassay increased7%QoQ.Mindray’s combined share in chemistry,immunoassay and coagulation hasincreased from10%in1H25to15%in3Q26,according to the Company.Domestic TLA new orders and installations were nearly400and300in9M26,respectively,which have surpassed the total in FY25.We think these will supportfuture reagent volume growth.Moreover,domestic emerging business reportedrevenue growth of20%YoY in9M26.As channel destocking is expected tolargely complete by year-end,we expect domestic growth to improve in2027E,led by IVD share gains and continued expansion in emerging businesses.

  Emerging businesses are becoming a more meaningful growth contributor.Revenue from emerging businesses grew20.5%YoY to RMB4.7bn in9M26,andreached17.5%of total sales.Minimally invasive surgery and intervention bothgrew more than20%YoY,with surgical high-value consumables more thandoubled and PFA procedures exceeded10,000in9M26.We see emergingbusinesses as an increasingly important driver of Mindray’s medium-termearnings growth.

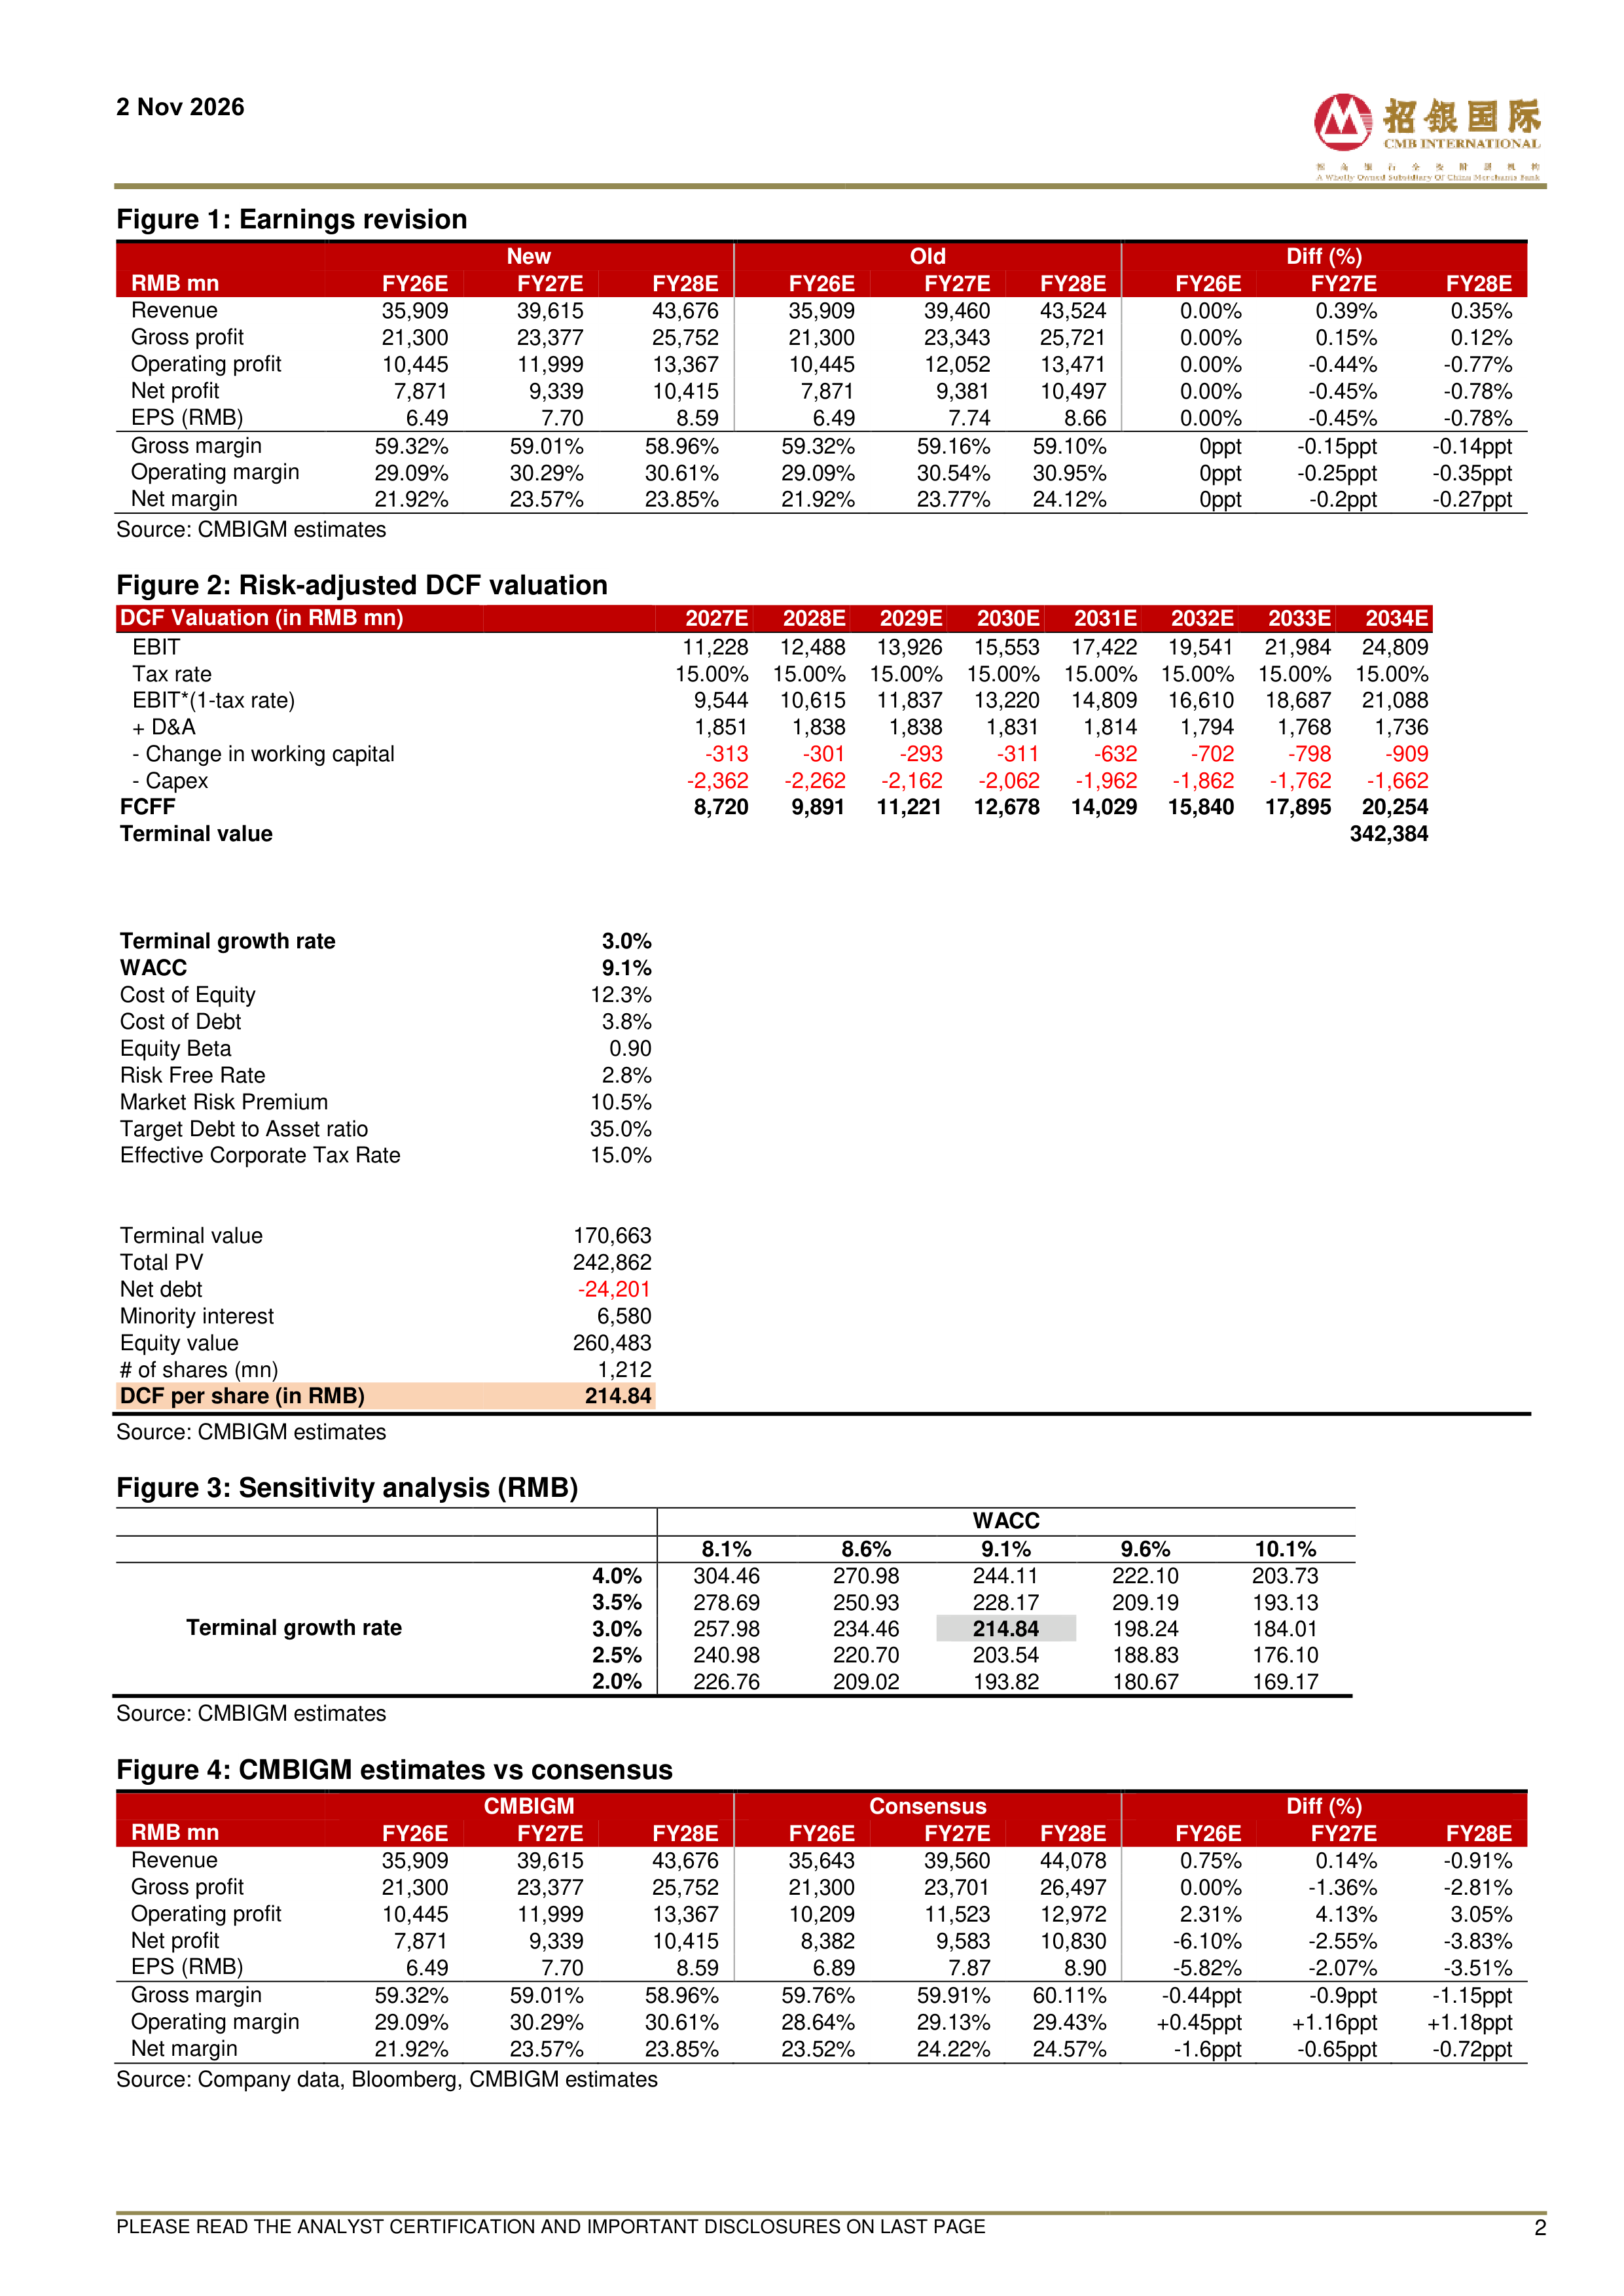
  Maintain BUY.We roll forward our DCF model to2027E-34E from2026E-34E,as valuation is increasingly anchored on2027E.We cut our earnings forecastsmodestly to reflect raw-material cost pressure.Therefore,we derive our TP ofRMB214.84based on an8-year DCF model.Key risks include FX volatility,IVDpricing pressure,weaker hospital procurement and slower overseas expansion.


报告正文
摩熵医药企业版
9大数据库,200+子数据库,一站查询药品研发、临床、上市、销售、投资、政策等数据了解更多
我要试用
1 / 5
试读已结束,如需全文阅读可点击
下载全文
如果您有其他需求,请点击
定制服务咨询
CMB International Capital Corporation Limited最新报告
关于摩熵咨询

摩熵咨询是摩熵数科旗下生物医药专业咨询服务品牌,由深耕医药领域多年的专业人士组成,核心成员均来自国际顶级咨询机构和行业标杆企业,涵盖立项、市场、战略、投资等从业背景,依托摩熵数科丰富的外部专家资源及全面的医药全产业链数据库,为客户提供专业咨询服务和定制化解决方案

1W+
医药行业研究报告
200+
真实项目案例
1300+
业内高端专家资源
市场洞察与营销赋能
市场洞察与营销赋能
分析市场现状,洞察行业趋势,依托数据分析和深度研究,辅助商业决策。
立项评估及管线规划
立项评估及管线规划
提供疾病领域品种调研、专家访谈、品种立项、项目交易整套服务。
产业规划及研究服务
产业规划及研究服务
以数据为基础,为组织、园区、企业提供科学的决策依据和趋势线索。
多渠道数据分析及定制服务
多渠道数据分析及定制服务
帮助客户深入了解目标领域和市场情况,发现潜在机会,优化企业决策。
投资决策与交易估值
投资决策与交易估值
依托全球医药全产业链数据库与顶级投行级分析模型,为并购、融资、IPO提供全周期决策支持。
立即定制

标签云

洞察市场格局
解锁药品研发情报

400客服电话

  • 定制咨询业务

    400-9696-311 转2

  • 数据与AI定制业务

    400-9696-311 转3