2025中国医药研发创新与营销创新峰会
Resilient demand driving accelerated growth in 3Q26

Resilient demand driving accelerated growth in 3Q26

研报

Resilient demand driving accelerated growth in 3Q26

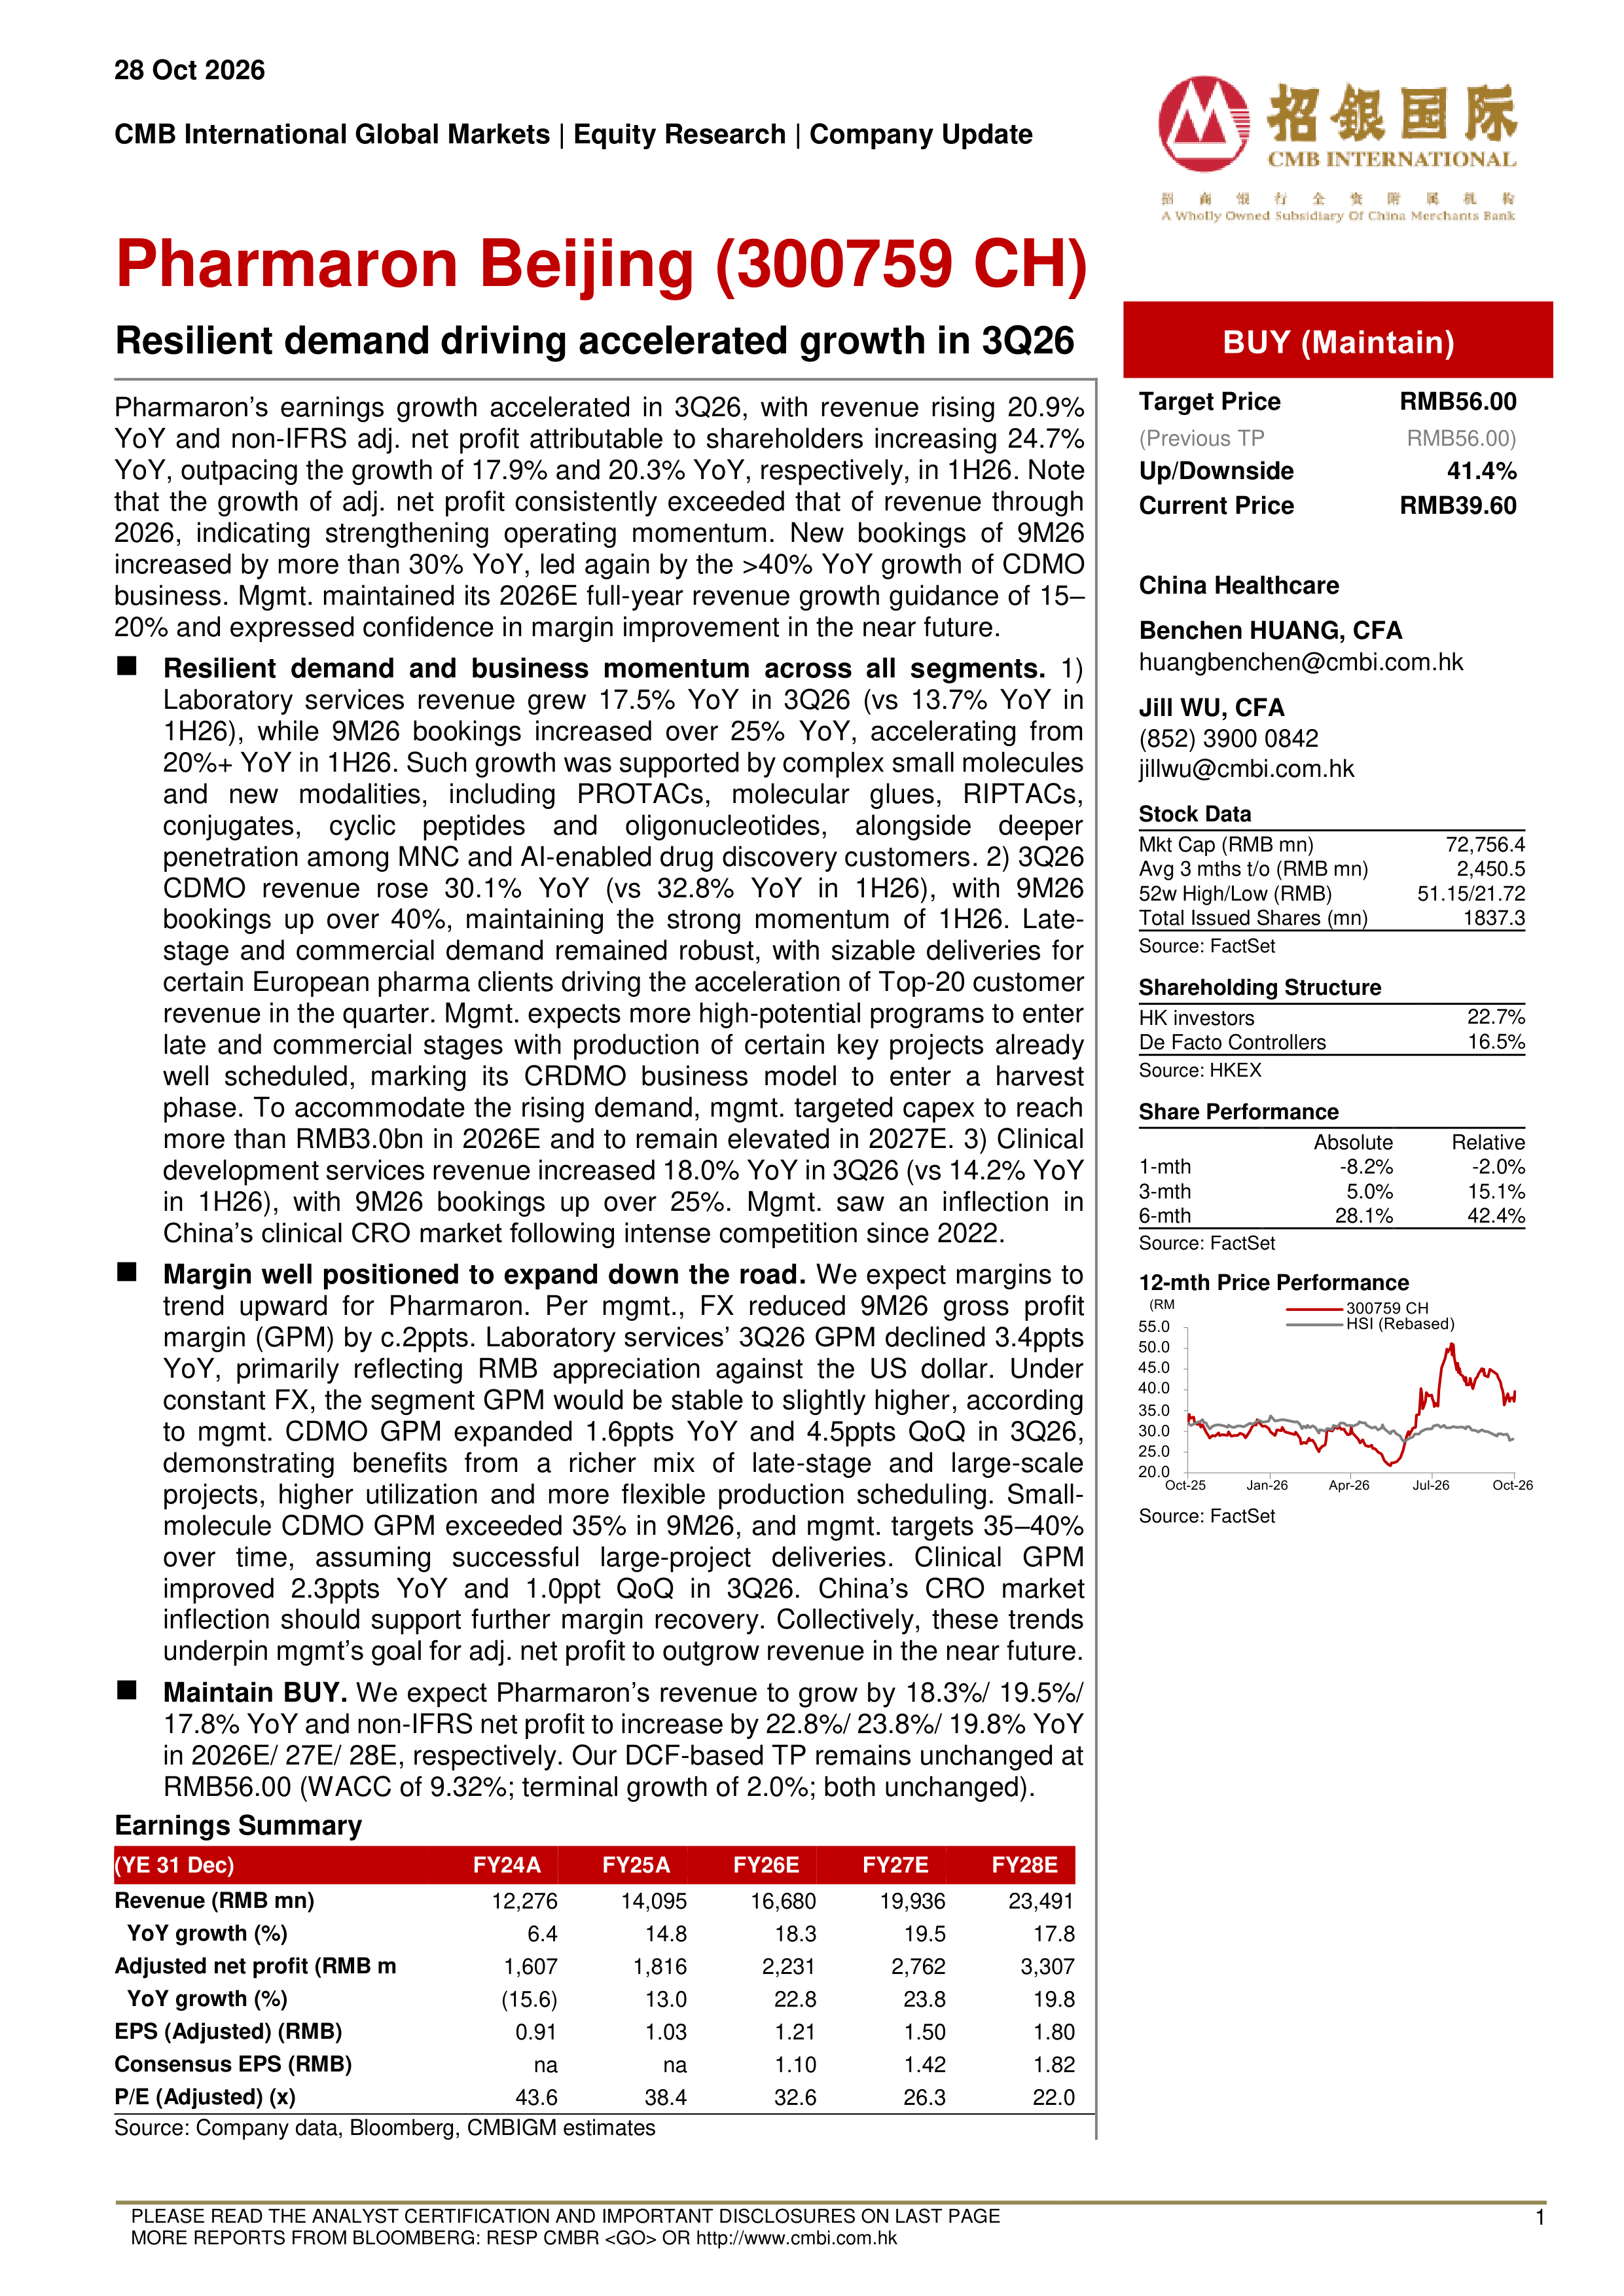
  康龙化成(300759)   Pharmaron’s earnings growth accelerated in3Q26,with revenue rising20.9%YoY and non-IFRS adj.net profit attributable to shareholders increasing24.7%YoY,outpacing the growth of17.9%and20.3%YoY,respectively,in1H26.Notethat the growth of adj.net profit consistently exceeded that of revenue through2026,indicating strengthening operating momentum.New bookings of9M26increased by more than30%YoY,led again by the>40%YoY growth of CDMObusiness.Mgmt.maintained its2026E full-year revenue growth guidance of15–20%and expressed confidence in margin improvement in the near future.   Resilient demand and business momentum across all segments.1)Laboratory services revenue grew17.5%YoY in3Q26(vs13.7%YoY in1H26),while9M26bookings increased over25%YoY,accelerating from20%+YoY in1H26.Such growth was supported by complex small moleculesand new modalities,including PROTACs,molecular glues,RIPTACs,conjugates,cyclic peptides and oligonucleotides,alongside deeperpenetration among MNC and AI-enabled drug discovery customers.2)3Q26CDMO revenue rose30.1%YoY(vs32.8%YoY in1H26),with9M26bookings up over40%,maintaining the strong momentum of1H26.Late-stage and commercial demand remained robust,with sizable deliveries forcertain European pharma clients driving the acceleration of Top-20customerrevenue in the quarter.Mgmt.expects more high-potential programs to enterlate and commercial stages with production of certain key projects alreadywell scheduled,marking its CRDMO business model to enter a harvestphase.To accommodate the rising demand,mgmt.targeted capex to reachmore than RMB3.0bn in2026E and to remain elevated in2027E.3)Clinicaldevelopment services revenue increased18.0%YoY in3Q26(vs14.2%YoYin1H26),with9M26bookings up over25%.Mgmt.saw an inflection inChina’s clinical CRO market following intense competition since2022.   Margin well positioned to expand down the road.We expect margins totrend upward for Pharmaron.Per mgmt.,FX reduced9M26gross profitmargin(GPM)by c.2ppts.Laboratory services’3Q26GPM declined3.4pptsYoY,primarily reflecting RMB appreciation against the US dollar.Underconstant FX,the segment GPM would be stable to slightly higher,accordingto mgmt.CDMO GPM expanded1.6ppts YoY and4.5ppts QoQ in3Q26,demonstrating benefits from a richer mix of late-stage and large-scaleprojects,higher utilization and more flexible production scheduling.Small-molecule CDMO GPM exceeded35%in9M26,and mgmt.targets35–40%over time,assuming successful large-project deliveries.Clinical GPMimproved2.3ppts YoY and1.0ppt QoQ in3Q26.China’s CRO marketinflection should support further margin recovery.Collectively,these trendsunderpin mgmt’s goal for adj.net profit to outgrow revenue in the near future.   Maintain BUY.We expect Pharmaron’s revenue to grow by18.3%/19.5%/17.8%YoY and non-IFRS net profit to increase by22.8%/23.8%/19.8%YoYin2026E/27E/28E,respectively.Our DCF-based TP remains unchanged atRMB56.00(WACC of9.32%;terminal growth of2.0%;both unchanged).

报告专题:
  • 下载次数:

    798 次

  • 发布机构:

    CMB International Capital Corporation Limited

  • 发布日期:

    2026-10-28

  • 页数:

    6页

下载全文
定制咨询
报告内容
报告摘要

  康龙化成(300759)

  Pharmaron’s earnings growth accelerated in3Q26,with revenue rising20.9%YoY and non-IFRS adj.net profit attributable to shareholders increasing24.7%YoY,outpacing the growth of17.9%and20.3%YoY,respectively,in1H26.Notethat the growth of adj.net profit consistently exceeded that of revenue through2026,indicating strengthening operating momentum.New bookings of9M26increased by more than30%YoY,led again by the>40%YoY growth of CDMObusiness.Mgmt.maintained its2026E full-year revenue growth guidance of15–20%and expressed confidence in margin improvement in the near future.

  Resilient demand and business momentum across all segments.1)Laboratory services revenue grew17.5%YoY in3Q26(vs13.7%YoY in1H26),while9M26bookings increased over25%YoY,accelerating from20%+YoY in1H26.Such growth was supported by complex small moleculesand new modalities,including PROTACs,molecular glues,RIPTACs,conjugates,cyclic peptides and oligonucleotides,alongside deeperpenetration among MNC and AI-enabled drug discovery customers.2)3Q26CDMO revenue rose30.1%YoY(vs32.8%YoY in1H26),with9M26bookings up over40%,maintaining the strong momentum of1H26.Late-stage and commercial demand remained robust,with sizable deliveries forcertain European pharma clients driving the acceleration of Top-20customerrevenue in the quarter.Mgmt.expects more high-potential programs to enterlate and commercial stages with production of certain key projects alreadywell scheduled,marking its CRDMO business model to enter a harvestphase.To accommodate the rising demand,mgmt.targeted capex to reachmore than RMB3.0bn in2026E and to remain elevated in2027E.3)Clinicaldevelopment services revenue increased18.0%YoY in3Q26(vs14.2%YoYin1H26),with9M26bookings up over25%.Mgmt.saw an inflection inChina’s clinical CRO market following intense competition since2022.

  Margin well positioned to expand down the road.We expect margins totrend upward for Pharmaron.Per mgmt.,FX reduced9M26gross profitmargin(GPM)by c.2ppts.Laboratory services’3Q26GPM declined3.4pptsYoY,primarily reflecting RMB appreciation against the US dollar.Underconstant FX,the segment GPM would be stable to slightly higher,accordingto mgmt.CDMO GPM expanded1.6ppts YoY and4.5ppts QoQ in3Q26,demonstrating benefits from a richer mix of late-stage and large-scaleprojects,higher utilization and more flexible production scheduling.Small-molecule CDMO GPM exceeded35%in9M26,and mgmt.targets35–40%over time,assuming successful large-project deliveries.Clinical GPMimproved2.3ppts YoY and1.0ppt QoQ in3Q26.China’s CRO marketinflection should support further margin recovery.Collectively,these trendsunderpin mgmt’s goal for adj.net profit to outgrow revenue in the near future.

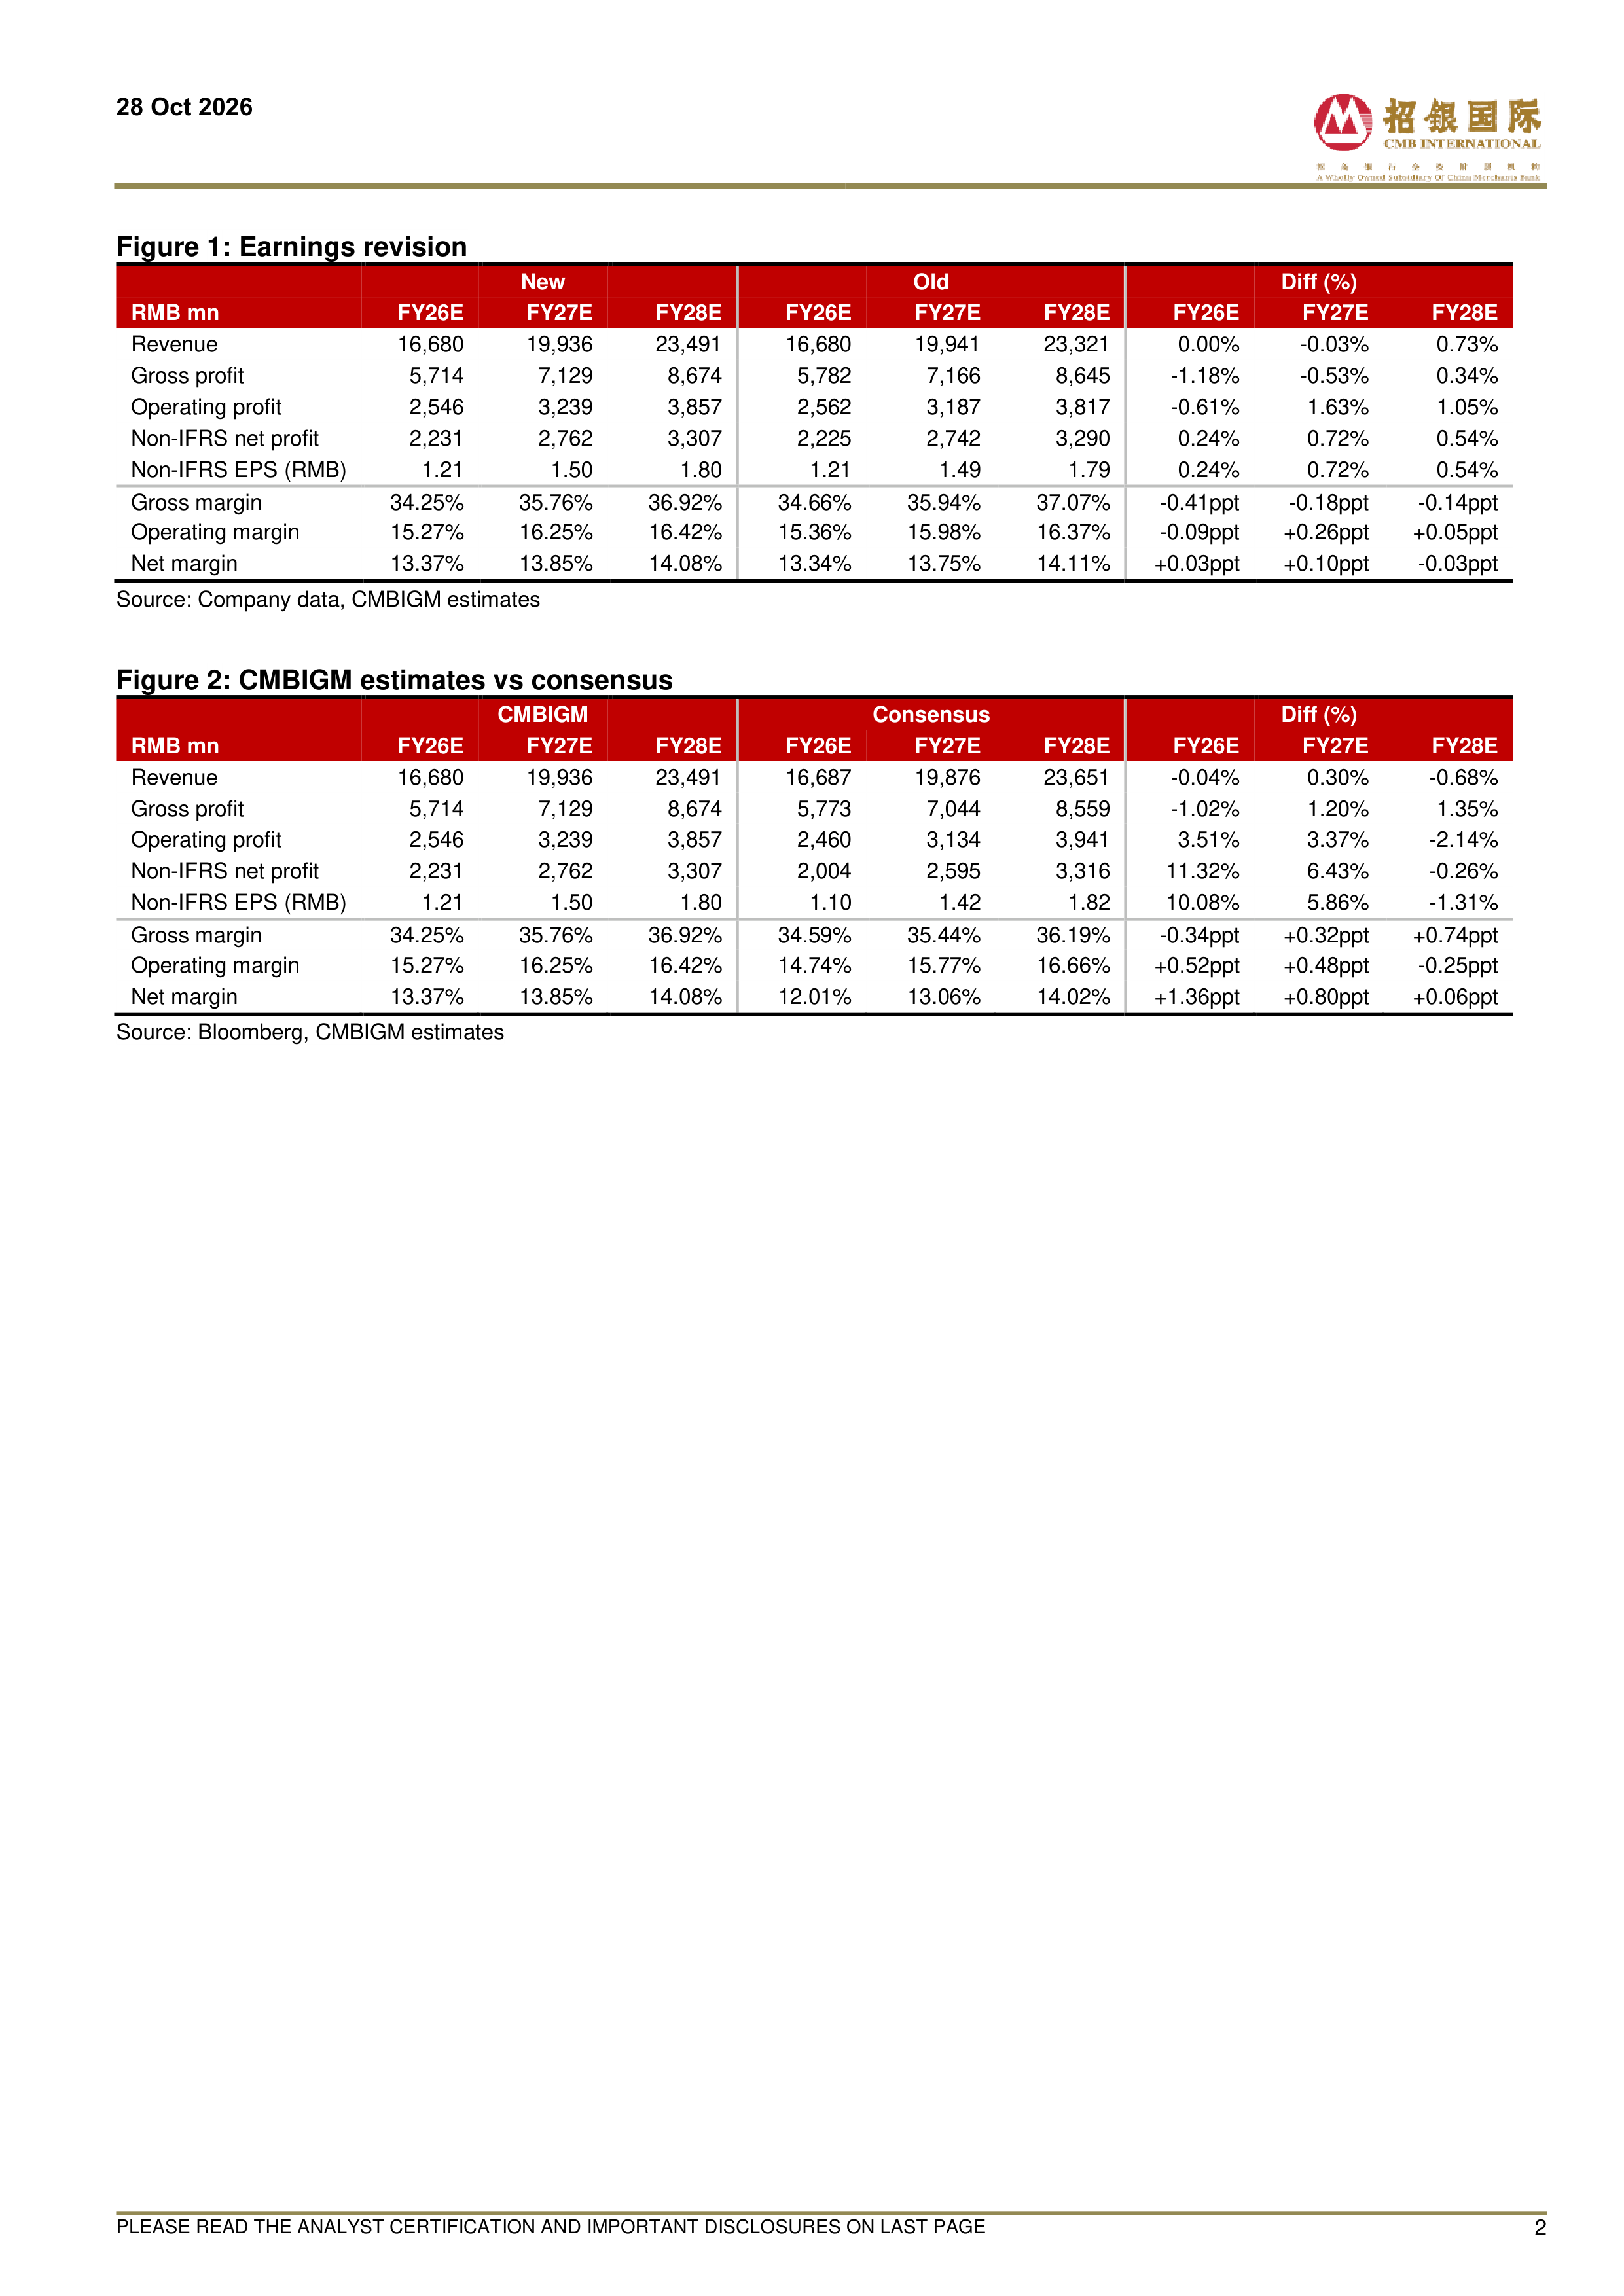
  Maintain BUY.We expect Pharmaron’s revenue to grow by18.3%/19.5%/17.8%YoY and non-IFRS net profit to increase by22.8%/23.8%/19.8%YoYin2026E/27E/28E,respectively.Our DCF-based TP remains unchanged atRMB56.00(WACC of9.32%;terminal growth of2.0%;both unchanged).


报告正文
摩熵医药企业版
9大数据库,200+子数据库,一站查询药品研发、临床、上市、销售、投资、政策等数据了解更多
我要试用
1 / 6
试读已结束,如需全文阅读可点击
下载全文
如果您有其他需求,请点击
定制服务咨询
CMB International Capital Corporation Limited最新报告
关于摩熵咨询

摩熵咨询是摩熵数科旗下生物医药专业咨询服务品牌,由深耕医药领域多年的专业人士组成,核心成员均来自国际顶级咨询机构和行业标杆企业,涵盖立项、市场、战略、投资等从业背景,依托摩熵数科丰富的外部专家资源及全面的医药全产业链数据库,为客户提供专业咨询服务和定制化解决方案

1W+
医药行业研究报告
200+
真实项目案例
1300+
业内高端专家资源
市场洞察与营销赋能
市场洞察与营销赋能
分析市场现状,洞察行业趋势,依托数据分析和深度研究,辅助商业决策。
立项评估及管线规划
立项评估及管线规划
提供疾病领域品种调研、专家访谈、品种立项、项目交易整套服务。
产业规划及研究服务
产业规划及研究服务
以数据为基础,为组织、园区、企业提供科学的决策依据和趋势线索。
多渠道数据分析及定制服务
多渠道数据分析及定制服务
帮助客户深入了解目标领域和市场情况,发现潜在机会,优化企业决策。
投资决策与交易估值
投资决策与交易估值
依托全球医药全产业链数据库与顶级投行级分析模型,为并购、融资、IPO提供全周期决策支持。
立即定制

标签云

洞察市场格局
解锁药品研发情报

400客服电话

  • 定制咨询业务

    400-9696-311 转2

  • 数据与AI定制业务

    400-9696-311 转3