2025中国医药研发创新与营销创新峰会
Overseas strength offsets domestic pressure; eyes on upcoming national VBP

Overseas strength offsets domestic pressure; eyes on upcoming national VBP

研报

Overseas strength offsets domestic pressure; eyes on upcoming national VBP

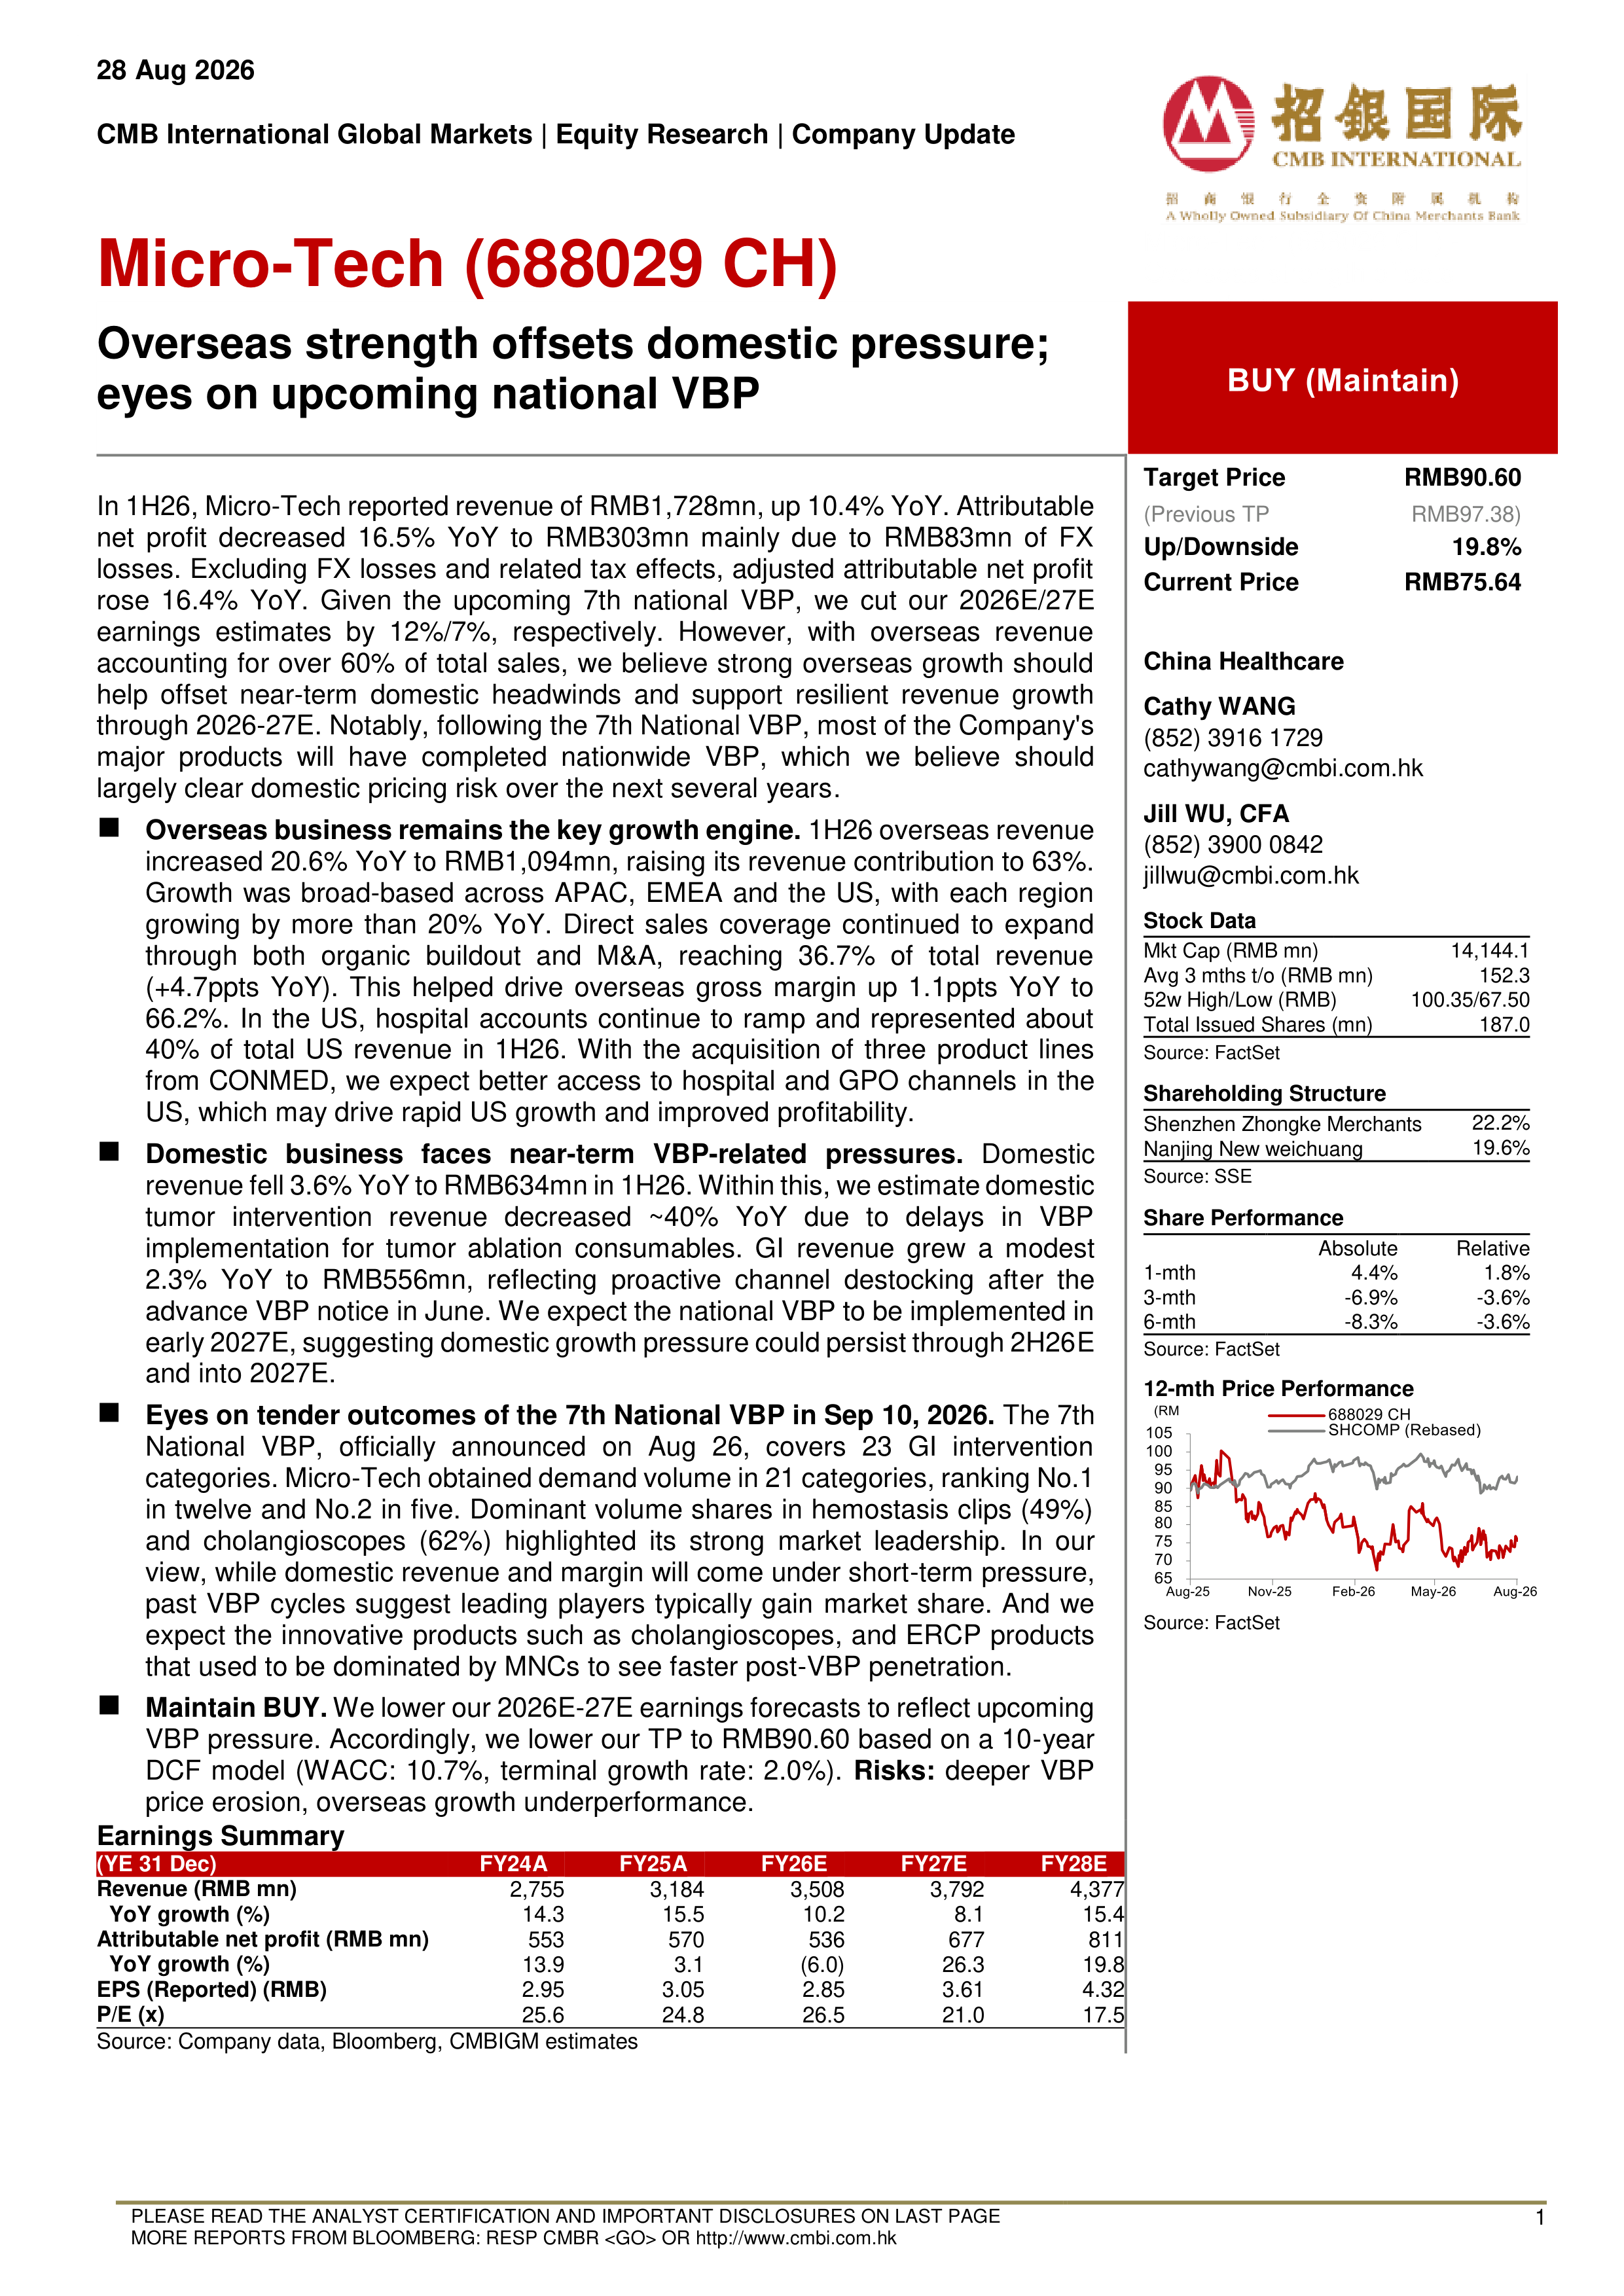
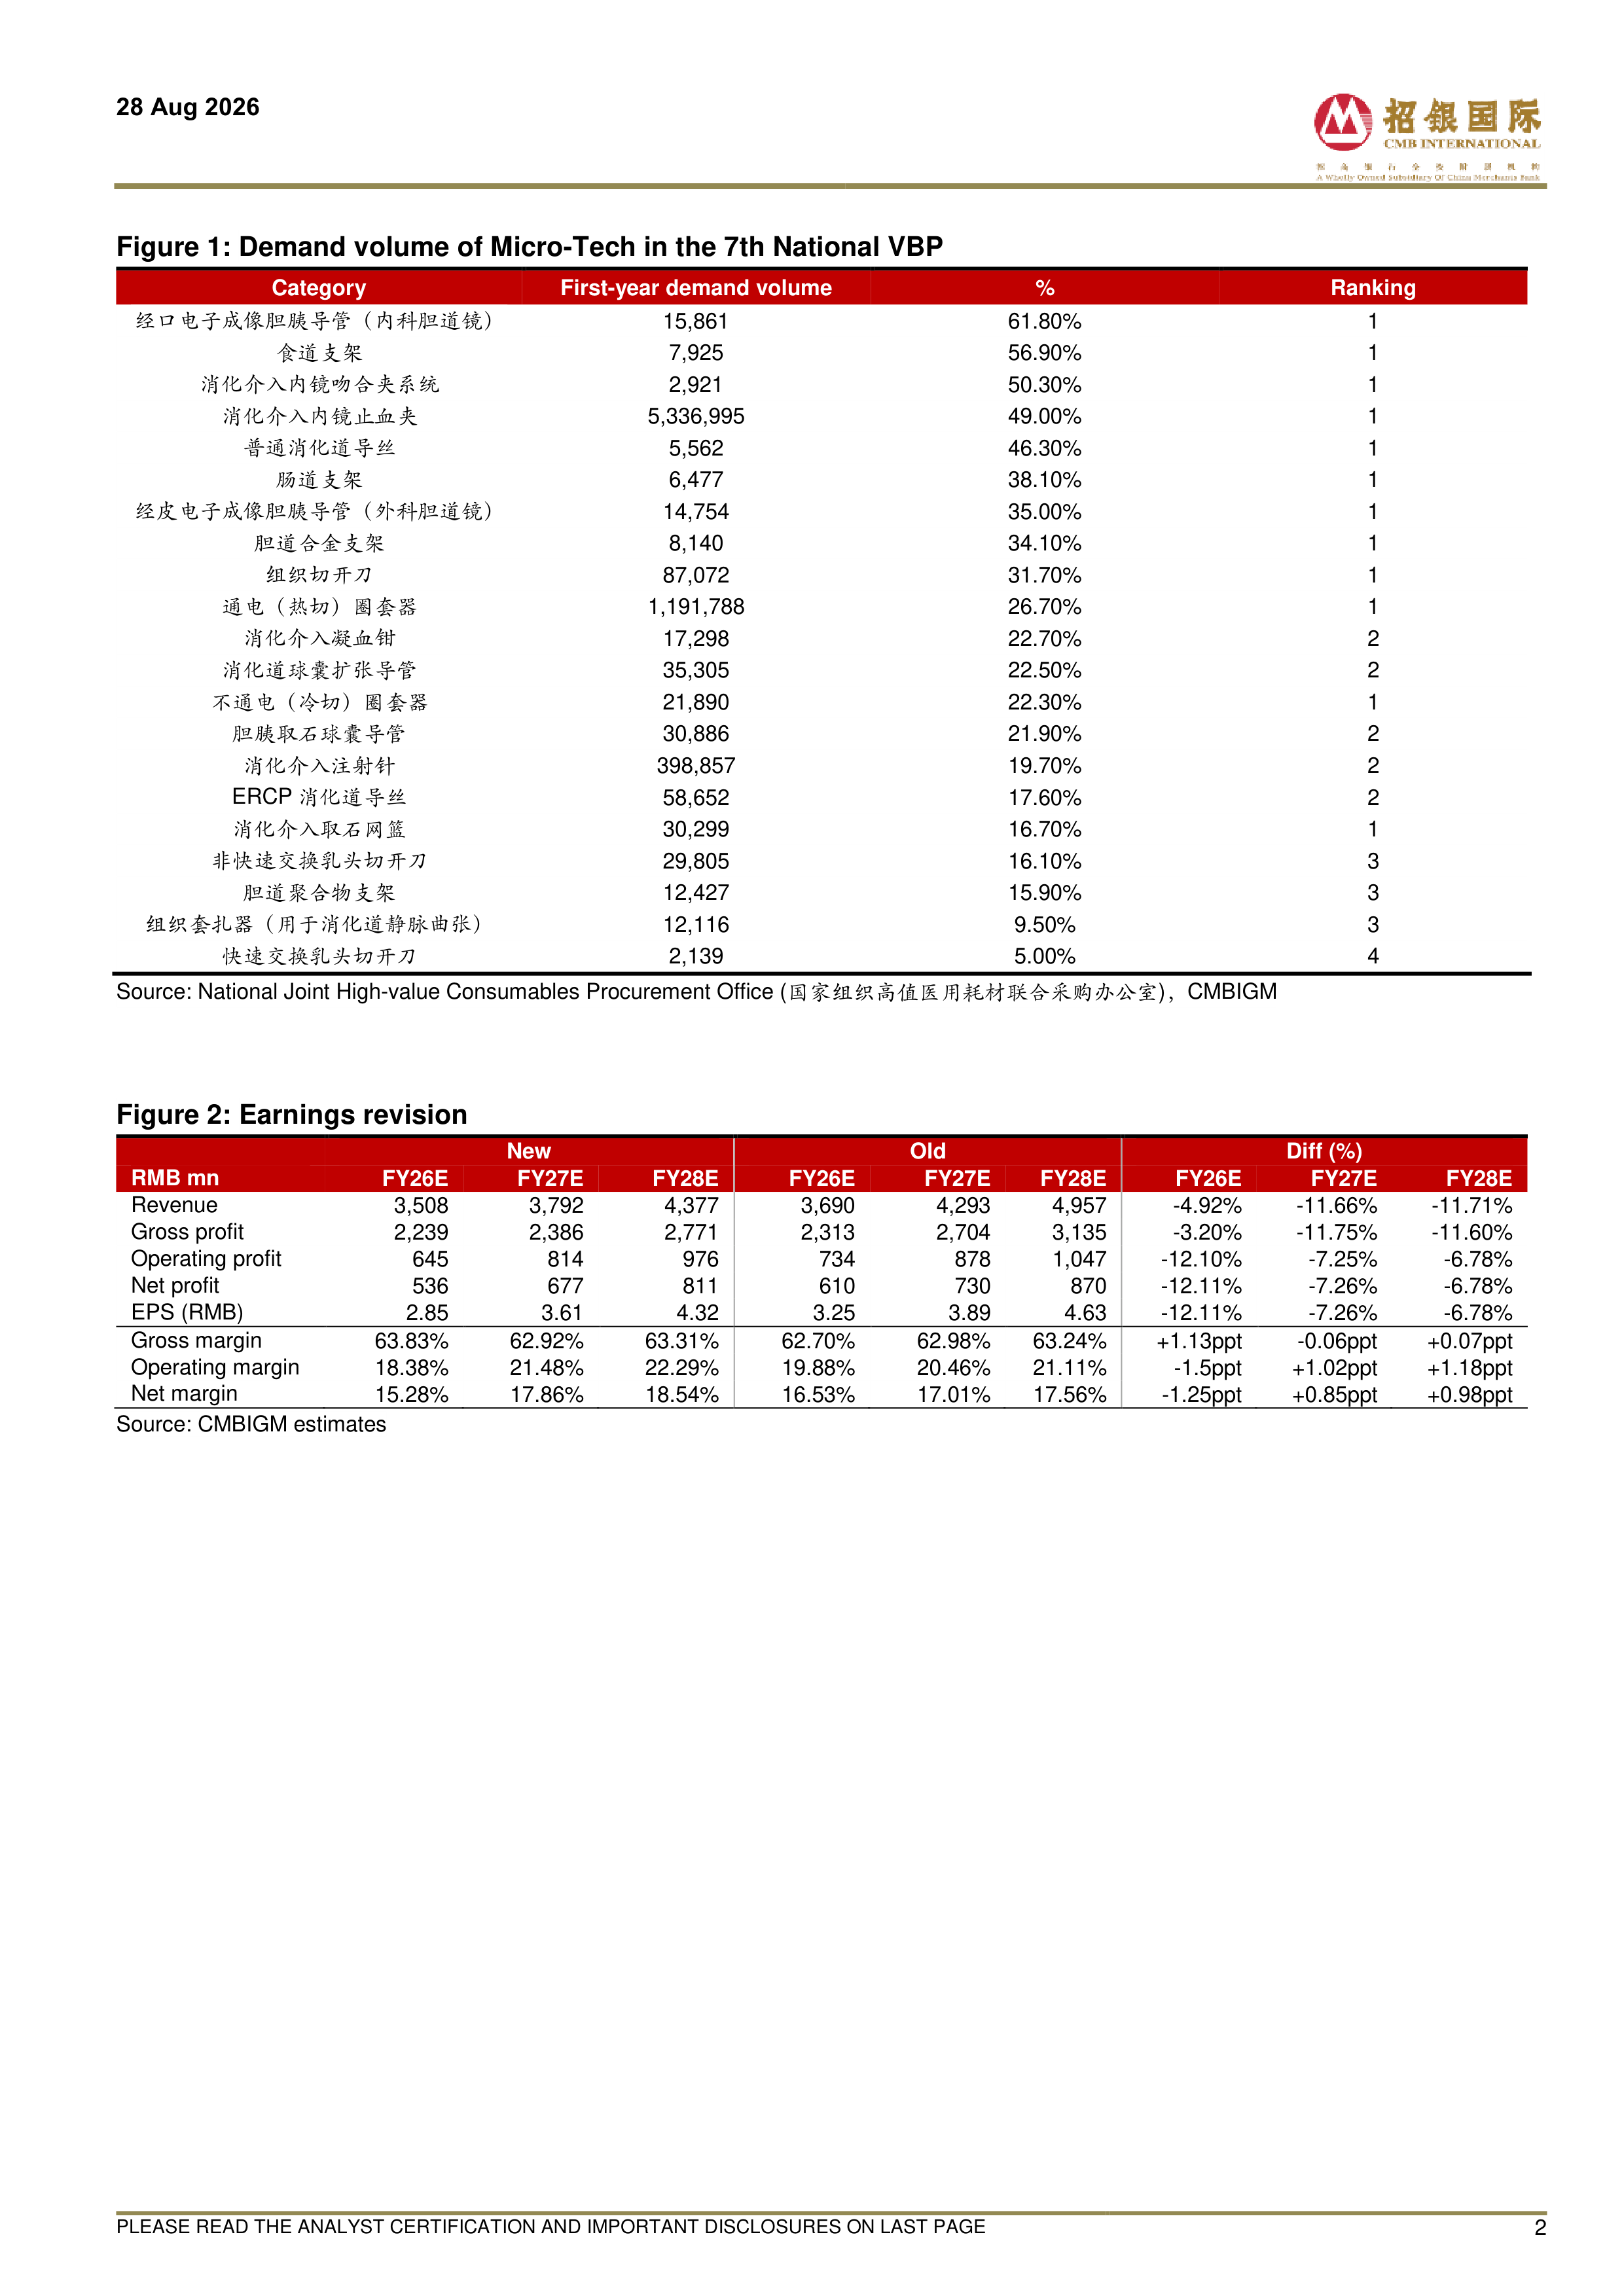
  南微医学(688029)   In 1H26, Micro-Tech reported revenue of RMB1,728mn, up 10.4% YoY. Attributablenet profit decreased 16.5% YoY to RMB303mn mainly due to RMB83mn of FXlosses. Excluding FX losses and related tax effects, adjusted attributable net profitrose 16.4% YoY. Given the upcoming 7th national VBP, we cut our 2026E/27Eearnings estimates by 12%/7%, respectively. However, with overseas revenueaccounting for over 60% of total sales, we believe strong overseas growth shouldhelp offset near-term domestic headwinds and support resilient revenue growththrough 2026-27E. Notably, following the 7th National VBP, most of the Company'smajor products will have completed nationwide VBP, which we believe shouldlargely clear domestic pricing risk over the next several years.   Overseas business remains the key growth engine. 1H26 overseas revenueincreased 20.6% YoY to RMB1,094mn, raising its revenue contribution to 63%.Growth was broad-based across APAC, EMEA and the US, with each regiongrowing by more than 20% YoY. Direct sales coverage continued to expandthrough both organic buildout and M&A, reaching 36.7% of total revenue(+4.7ppts YoY). This helped drive overseas gross margin up 1.1ppts YoY to66.2%. In the US, hospital accounts continue to ramp and represented about40% of total US revenue in 1H26. With the acquisition of three product linesfrom CONMED, we expect better access to hospital and GPO channels in theUS, which may drive rapid US growth and improved profitability.   Domestic business faces near-term VBP-related pressures. Domesticrevenue fell 3.6% YoY to RMB634mn in 1H26. Within this, we estimate domestictumor intervention revenue decreased ~40% YoY due to delays in VBPimplementation for tumor ablation consumables. GI revenue grew a modest2.3% YoY to RMB556mn, reflecting proactive channel destocking after theadvance VBP notice in June. We expect the national VBP to be implemented inearly 2027E, suggesting domestic growth pressure could persist through 2H26Eand into 2027E.   Eyes on tender outcomes of the 7th National VBP in Sep 10, 2026. The 7thNational VBP, officially announced on Aug 26, covers 23 GI interventioncategories. Micro-Tech obtained demand volume in 21 categories, ranking No.1in twelve and No.2 in five. Dominant volume shares in hemostasis clips (49%)and cholangioscopes (62%) highlighted its strong market leadership. In ourview, while domestic revenue and margin will come under short-term pressure,past VBP cycles suggest leading players typically gain market share. And weexpect the innovative products such as cholangioscopes, and ERCP productsthat used to be dominated by MNCs to see faster post-VBP penetration.   Maintain BUY. We lower our 2026E-27E earnings forecasts to reflect upcomingVBP pressure. Accordingly, we lower our TP to RMB90.60 based on a 10-yearDCF model (WACC: 10.7%, terminal growth rate: 2.0%). Risks: deeper VBPprice erosion, overseas growth underperformance.

报告专题:
  • 下载次数:

    2377 次

  • 发布机构:

    CMB International Capital Corporation Limited

  • 发布日期:

    2026-08-28

  • 页数:

    6页

下载全文
定制咨询
报告内容
报告摘要

  南微医学(688029)

  In 1H26, Micro-Tech reported revenue of RMB1,728mn, up 10.4% YoY. Attributablenet profit decreased 16.5% YoY to RMB303mn mainly due to RMB83mn of FXlosses. Excluding FX losses and related tax effects, adjusted attributable net profitrose 16.4% YoY. Given the upcoming 7th national VBP, we cut our 2026E/27Eearnings estimates by 12%/7%, respectively. However, with overseas revenueaccounting for over 60% of total sales, we believe strong overseas growth shouldhelp offset near-term domestic headwinds and support resilient revenue growththrough 2026-27E. Notably, following the 7th National VBP, most of the Company'smajor products will have completed nationwide VBP, which we believe shouldlargely clear domestic pricing risk over the next several years.

  Overseas business remains the key growth engine. 1H26 overseas revenueincreased 20.6% YoY to RMB1,094mn, raising its revenue contribution to 63%.Growth was broad-based across APAC, EMEA and the US, with each regiongrowing by more than 20% YoY. Direct sales coverage continued to expandthrough both organic buildout and M&A, reaching 36.7% of total revenue(+4.7ppts YoY). This helped drive overseas gross margin up 1.1ppts YoY to66.2%. In the US, hospital accounts continue to ramp and represented about40% of total US revenue in 1H26. With the acquisition of three product linesfrom CONMED, we expect better access to hospital and GPO channels in theUS, which may drive rapid US growth and improved profitability.

  Domestic business faces near-term VBP-related pressures. Domesticrevenue fell 3.6% YoY to RMB634mn in 1H26. Within this, we estimate domestictumor intervention revenue decreased ~40% YoY due to delays in VBPimplementation for tumor ablation consumables. GI revenue grew a modest2.3% YoY to RMB556mn, reflecting proactive channel destocking after theadvance VBP notice in June. We expect the national VBP to be implemented inearly 2027E, suggesting domestic growth pressure could persist through 2H26Eand into 2027E.

  Eyes on tender outcomes of the 7th National VBP in Sep 10, 2026. The 7thNational VBP, officially announced on Aug 26, covers 23 GI interventioncategories. Micro-Tech obtained demand volume in 21 categories, ranking No.1in twelve and No.2 in five. Dominant volume shares in hemostasis clips (49%)and cholangioscopes (62%) highlighted its strong market leadership. In ourview, while domestic revenue and margin will come under short-term pressure,past VBP cycles suggest leading players typically gain market share. And weexpect the innovative products such as cholangioscopes, and ERCP productsthat used to be dominated by MNCs to see faster post-VBP penetration.

  Maintain BUY. We lower our 2026E-27E earnings forecasts to reflect upcomingVBP pressure. Accordingly, we lower our TP to RMB90.60 based on a 10-yearDCF model (WACC: 10.7%, terminal growth rate: 2.0%). Risks: deeper VBPprice erosion, overseas growth underperformance.


报告正文
摩熵医药企业版
9大数据库,200+子数据库,一站查询药品研发、临床、上市、销售、投资、政策等数据了解更多
我要试用
1 / 6
试读已结束,如需全文阅读可点击
下载全文
如果您有其他需求,请点击
定制服务咨询
CMB International Capital Corporation Limited最新报告
关于摩熵咨询

摩熵咨询是摩熵数科旗下生物医药专业咨询服务品牌,由深耕医药领域多年的专业人士组成,核心成员均来自国际顶级咨询机构和行业标杆企业,涵盖立项、市场、战略、投资等从业背景,依托摩熵数科丰富的外部专家资源及全面的医药全产业链数据库,为客户提供专业咨询服务和定制化解决方案

1W+
医药行业研究报告
200+
真实项目案例
1300+
业内高端专家资源
市场洞察与营销赋能
市场洞察与营销赋能
分析市场现状,洞察行业趋势,依托数据分析和深度研究,辅助商业决策。
立项评估及管线规划
立项评估及管线规划
提供疾病领域品种调研、专家访谈、品种立项、项目交易整套服务。
产业规划及研究服务
产业规划及研究服务
以数据为基础,为组织、园区、企业提供科学的决策依据和趋势线索。
多渠道数据分析及定制服务
多渠道数据分析及定制服务
帮助客户深入了解目标领域和市场情况,发现潜在机会,优化企业决策。
投资决策与交易估值
投资决策与交易估值
依托全球医药全产业链数据库与顶级投行级分析模型,为并购、融资、IPO提供全周期决策支持。
立即定制

标签云

洞察市场格局
解锁药品研发情报

400客服电话

  • 定制咨询业务

    400-9696-311 转2

  • 数据与AI定制业务

    400-9696-311 转3