2025中国医药研发创新与营销创新峰会
Accelerated backlog growth with further guidance raise in 3Q26

Accelerated backlog growth with further guidance raise in 3Q26

研报

Accelerated backlog growth with further guidance raise in 3Q26

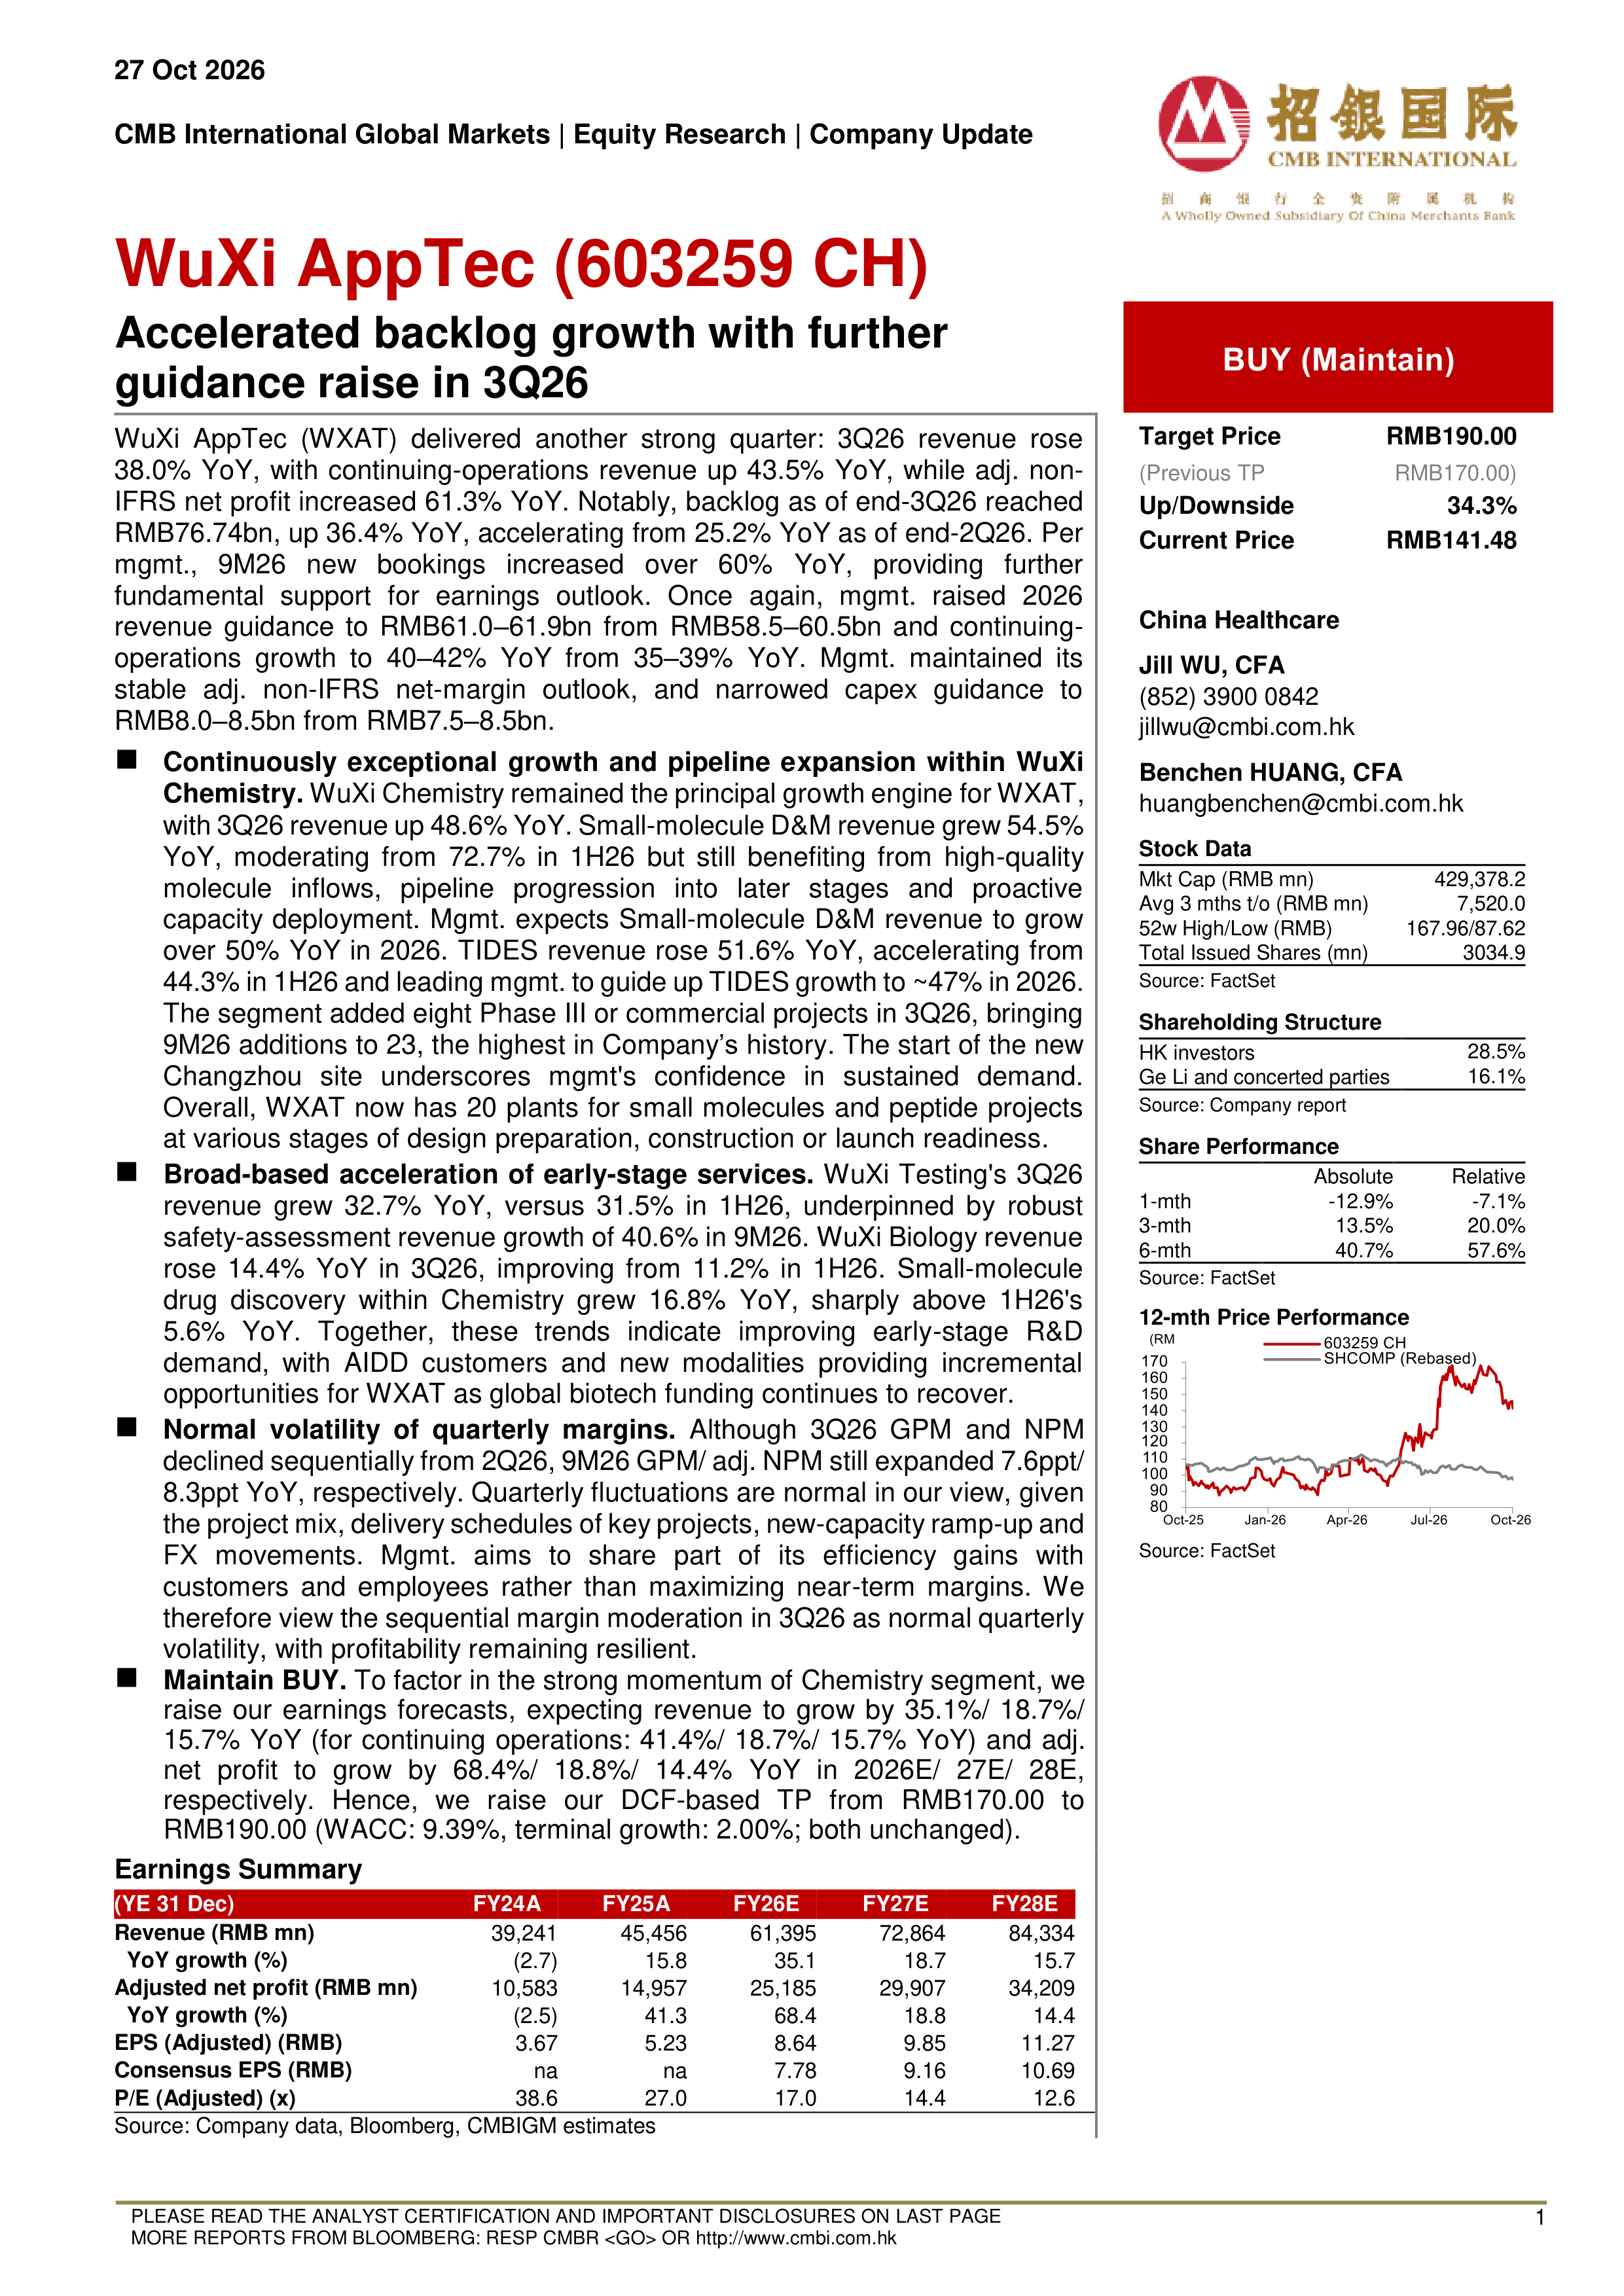
  药明康德(603259)   WuXi AppTec (WXAT) delivered another strong quarter: 3Q26 revenue rose38.0% YoY, with continuing-operations revenue up 43.5% YoY, while adj. nonIFRS net profit increased 61.3% YoY. Notably, backlog as of end-3Q26 reachedRMB76.74bn, up 36.4% YoY, accelerating from 25.2% YoY as of end-2Q26. Permgmt., 9M26 new bookings increased over 60% YoY, providing furtherfundamental support for earnings outlook. Once again, mgmt. raised 2026revenue guidance to RMB61.0–61.9bn from RMB58.5–60.5bn and continuingoperations growth to 40–42% YoY from 35–39% YoY. Mgmt. maintained itsstable adj. non-IFRS net-margin outlook, and narrowed capex guidance toRMB8.0–8.5bn from RMB7.5–8.5bn.   Continuously exceptional growth and pipeline expansion within WuXiChemistry. WuXi Chemistry remained the principal growth engine for WXAT,with 3Q26 revenue up 48.6% YoY. Small-molecule D&M revenue grew 54.5%YoY, moderating from 72.7% in 1H26 but still benefiting from high-qualitymolecule inflows, pipeline progression into later stages and proactivecapacity deployment. Mgmt. expects Small-molecule D&M revenue to growover 50% YoY in 2026. TIDES revenue rose 51.6% YoY, accelerating from44.3% in 1H26 and leading mgmt. to guide up TIDES growth to ~47% in 2026.The segment added eight Phase III or commercial projects in 3Q26, bringing9M26 additions to 23, the highest in Company’s history. The start of the newChangzhou site underscores mgmt's confidence in sustained demand.Overall, WXAT now has 20 plants for small molecules and peptide projectsat various stages of design preparation, construction or launch readiness.   Broad-based acceleration of early-stage services. WuXi Testing's 3Q26revenue grew 32.7% YoY, versus 31.5% in 1H26, underpinned by robustsafety-assessment revenue growth of 40.6% in 9M26. WuXi Biology revenuerose 14.4% YoY in 3Q26, improving from 11.2% in 1H26. Small-moleculedrug discovery within Chemistry grew 16.8% YoY, sharply above 1H26's5.6% YoY. Together, these trends indicate improving early-stage R&Ddemand, with AIDD customers and new modalities providing incrementalopportunities for WXAT as global biotech funding continues to recover.   Normal volatility of quarterly margins. Although 3Q26 GPM and NPMdeclined sequentially from 2Q26, 9M26 GPM/ adj. NPM still expanded 7.6ppt/8.3ppt YoY, respectively. Quarterly fluctuations are normal in our view, giventhe project mix, delivery schedules of key projects, new-capacity ramp-up andFX movements. Mgmt. aims to share part of its efficiency gains withcustomers and employees rather than maximizing near-term margins. Wetherefore view the sequential margin moderation in 3Q26 as normal quarterlyvolatility, with profitability remaining resilient.   Maintain BUY. To factor in the strong momentum of Chemistry segment, weraise our earnings forecasts, expecting revenue to grow by 35.1%/ 18.7%/15.7% YoY (for continuing operations: 41.4%/ 18.7%/ 15.7% YoY) and adj.net profit to grow by 68.4%/ 18.8%/ 14.4% YoY in 2026E/ 27E/ 28E,respectively. Hence, we raise our DCF-based TP from RMB170.00 toRMB190.00 (WACC: 9.39%, terminal growth: 2.00%; both unchanged)

报告标签:
  • 个股研报
报告专题:
  • 下载次数:

    1599 次

  • 发布机构:

    CMB International Capital Corporation Limited

  • 发布日期:

    2026-10-28

  • 页数:

    6页

下载全文
定制咨询
报告内容
报告摘要

  药明康德(603259)

  WuXi AppTec (WXAT) delivered another strong quarter: 3Q26 revenue rose38.0% YoY, with continuing-operations revenue up 43.5% YoY, while adj. nonIFRS net profit increased 61.3% YoY. Notably, backlog as of end-3Q26 reachedRMB76.74bn, up 36.4% YoY, accelerating from 25.2% YoY as of end-2Q26. Permgmt., 9M26 new bookings increased over 60% YoY, providing furtherfundamental support for earnings outlook. Once again, mgmt. raised 2026revenue guidance to RMB61.0–61.9bn from RMB58.5–60.5bn and continuingoperations growth to 40–42% YoY from 35–39% YoY. Mgmt. maintained itsstable adj. non-IFRS net-margin outlook, and narrowed capex guidance toRMB8.0–8.5bn from RMB7.5–8.5bn.

  Continuously exceptional growth and pipeline expansion within WuXiChemistry. WuXi Chemistry remained the principal growth engine for WXAT,with 3Q26 revenue up 48.6% YoY. Small-molecule D&M revenue grew 54.5%YoY, moderating from 72.7% in 1H26 but still benefiting from high-qualitymolecule inflows, pipeline progression into later stages and proactivecapacity deployment. Mgmt. expects Small-molecule D&M revenue to growover 50% YoY in 2026. TIDES revenue rose 51.6% YoY, accelerating from44.3% in 1H26 and leading mgmt. to guide up TIDES growth to ~47% in 2026.The segment added eight Phase III or commercial projects in 3Q26, bringing9M26 additions to 23, the highest in Company’s history. The start of the newChangzhou site underscores mgmt's confidence in sustained demand.Overall, WXAT now has 20 plants for small molecules and peptide projectsat various stages of design preparation, construction or launch readiness.

  Broad-based acceleration of early-stage services. WuXi Testing's 3Q26revenue grew 32.7% YoY, versus 31.5% in 1H26, underpinned by robustsafety-assessment revenue growth of 40.6% in 9M26. WuXi Biology revenuerose 14.4% YoY in 3Q26, improving from 11.2% in 1H26. Small-moleculedrug discovery within Chemistry grew 16.8% YoY, sharply above 1H26's5.6% YoY. Together, these trends indicate improving early-stage R&Ddemand, with AIDD customers and new modalities providing incrementalopportunities for WXAT as global biotech funding continues to recover.

  Normal volatility of quarterly margins. Although 3Q26 GPM and NPMdeclined sequentially from 2Q26, 9M26 GPM/ adj. NPM still expanded 7.6ppt/8.3ppt YoY, respectively. Quarterly fluctuations are normal in our view, giventhe project mix, delivery schedules of key projects, new-capacity ramp-up andFX movements. Mgmt. aims to share part of its efficiency gains withcustomers and employees rather than maximizing near-term margins. Wetherefore view the sequential margin moderation in 3Q26 as normal quarterlyvolatility, with profitability remaining resilient.

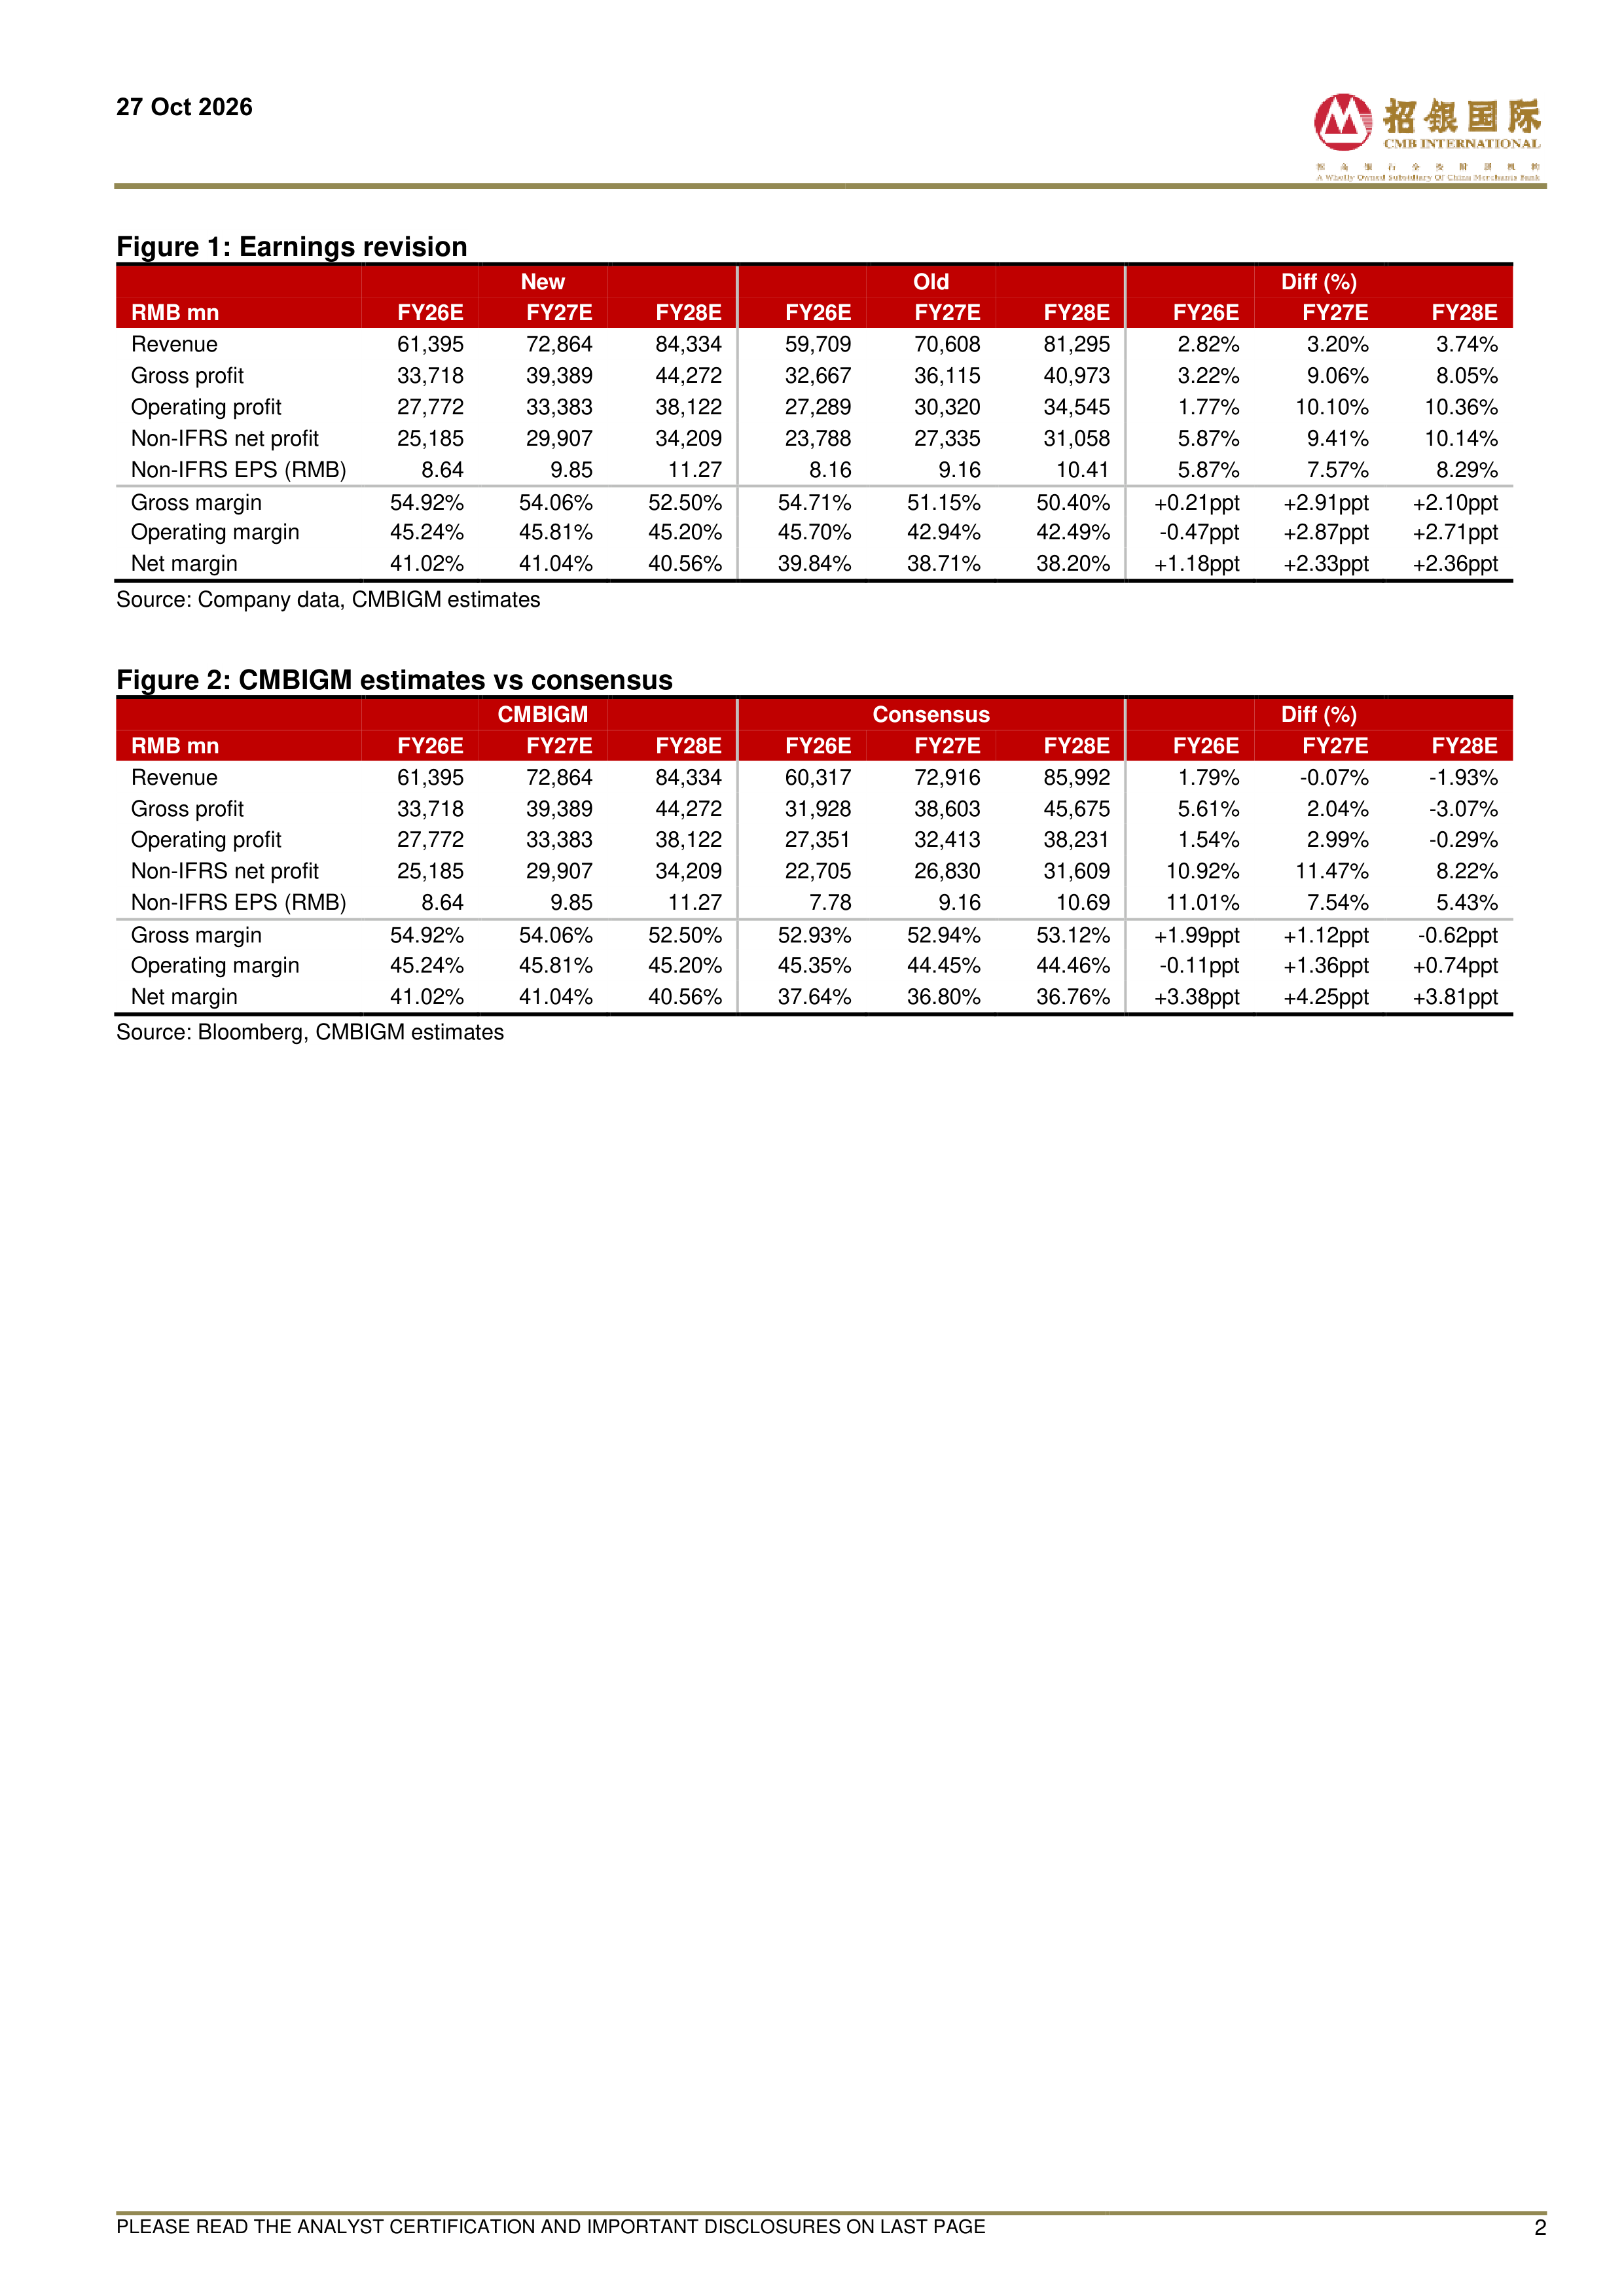
  Maintain BUY. To factor in the strong momentum of Chemistry segment, weraise our earnings forecasts, expecting revenue to grow by 35.1%/ 18.7%/15.7% YoY (for continuing operations: 41.4%/ 18.7%/ 15.7% YoY) and adj.net profit to grow by 68.4%/ 18.8%/ 14.4% YoY in 2026E/ 27E/ 28E,respectively. Hence, we raise our DCF-based TP from RMB170.00 toRMB190.00 (WACC: 9.39%, terminal growth: 2.00%; both unchanged)


报告正文
摩熵医药企业版
9大数据库,200+子数据库,一站查询药品研发、临床、上市、销售、投资、政策等数据了解更多
我要试用
1 / 6
试读已结束,如需全文阅读可点击
下载全文
如果您有其他需求,请点击
定制服务咨询
CMB International Capital Corporation Limited最新报告
关于摩熵咨询

摩熵咨询是摩熵数科旗下生物医药专业咨询服务品牌,由深耕医药领域多年的专业人士组成,核心成员均来自国际顶级咨询机构和行业标杆企业,涵盖立项、市场、战略、投资等从业背景,依托摩熵数科丰富的外部专家资源及全面的医药全产业链数据库,为客户提供专业咨询服务和定制化解决方案

1W+
医药行业研究报告
200+
真实项目案例
1300+
业内高端专家资源
市场洞察与营销赋能
市场洞察与营销赋能
分析市场现状,洞察行业趋势,依托数据分析和深度研究,辅助商业决策。
立项评估及管线规划
立项评估及管线规划
提供疾病领域品种调研、专家访谈、品种立项、项目交易整套服务。
产业规划及研究服务
产业规划及研究服务
以数据为基础,为组织、园区、企业提供科学的决策依据和趋势线索。
多渠道数据分析及定制服务
多渠道数据分析及定制服务
帮助客户深入了解目标领域和市场情况,发现潜在机会,优化企业决策。
投资决策与交易估值
投资决策与交易估值
依托全球医药全产业链数据库与顶级投行级分析模型,为并购、融资、IPO提供全周期决策支持。
立即定制

标签云

洞察市场格局
解锁药品研发情报

400客服电话

  • 定制咨询业务

    400-9696-311 转2

  • 数据与AI定制业务

    400-9696-311 转3