2025中国医药研发创新与营销创新峰会
Guidance raised on robust CDMO growth

Guidance raised on robust CDMO growth

研报

Guidance raised on robust CDMO growth

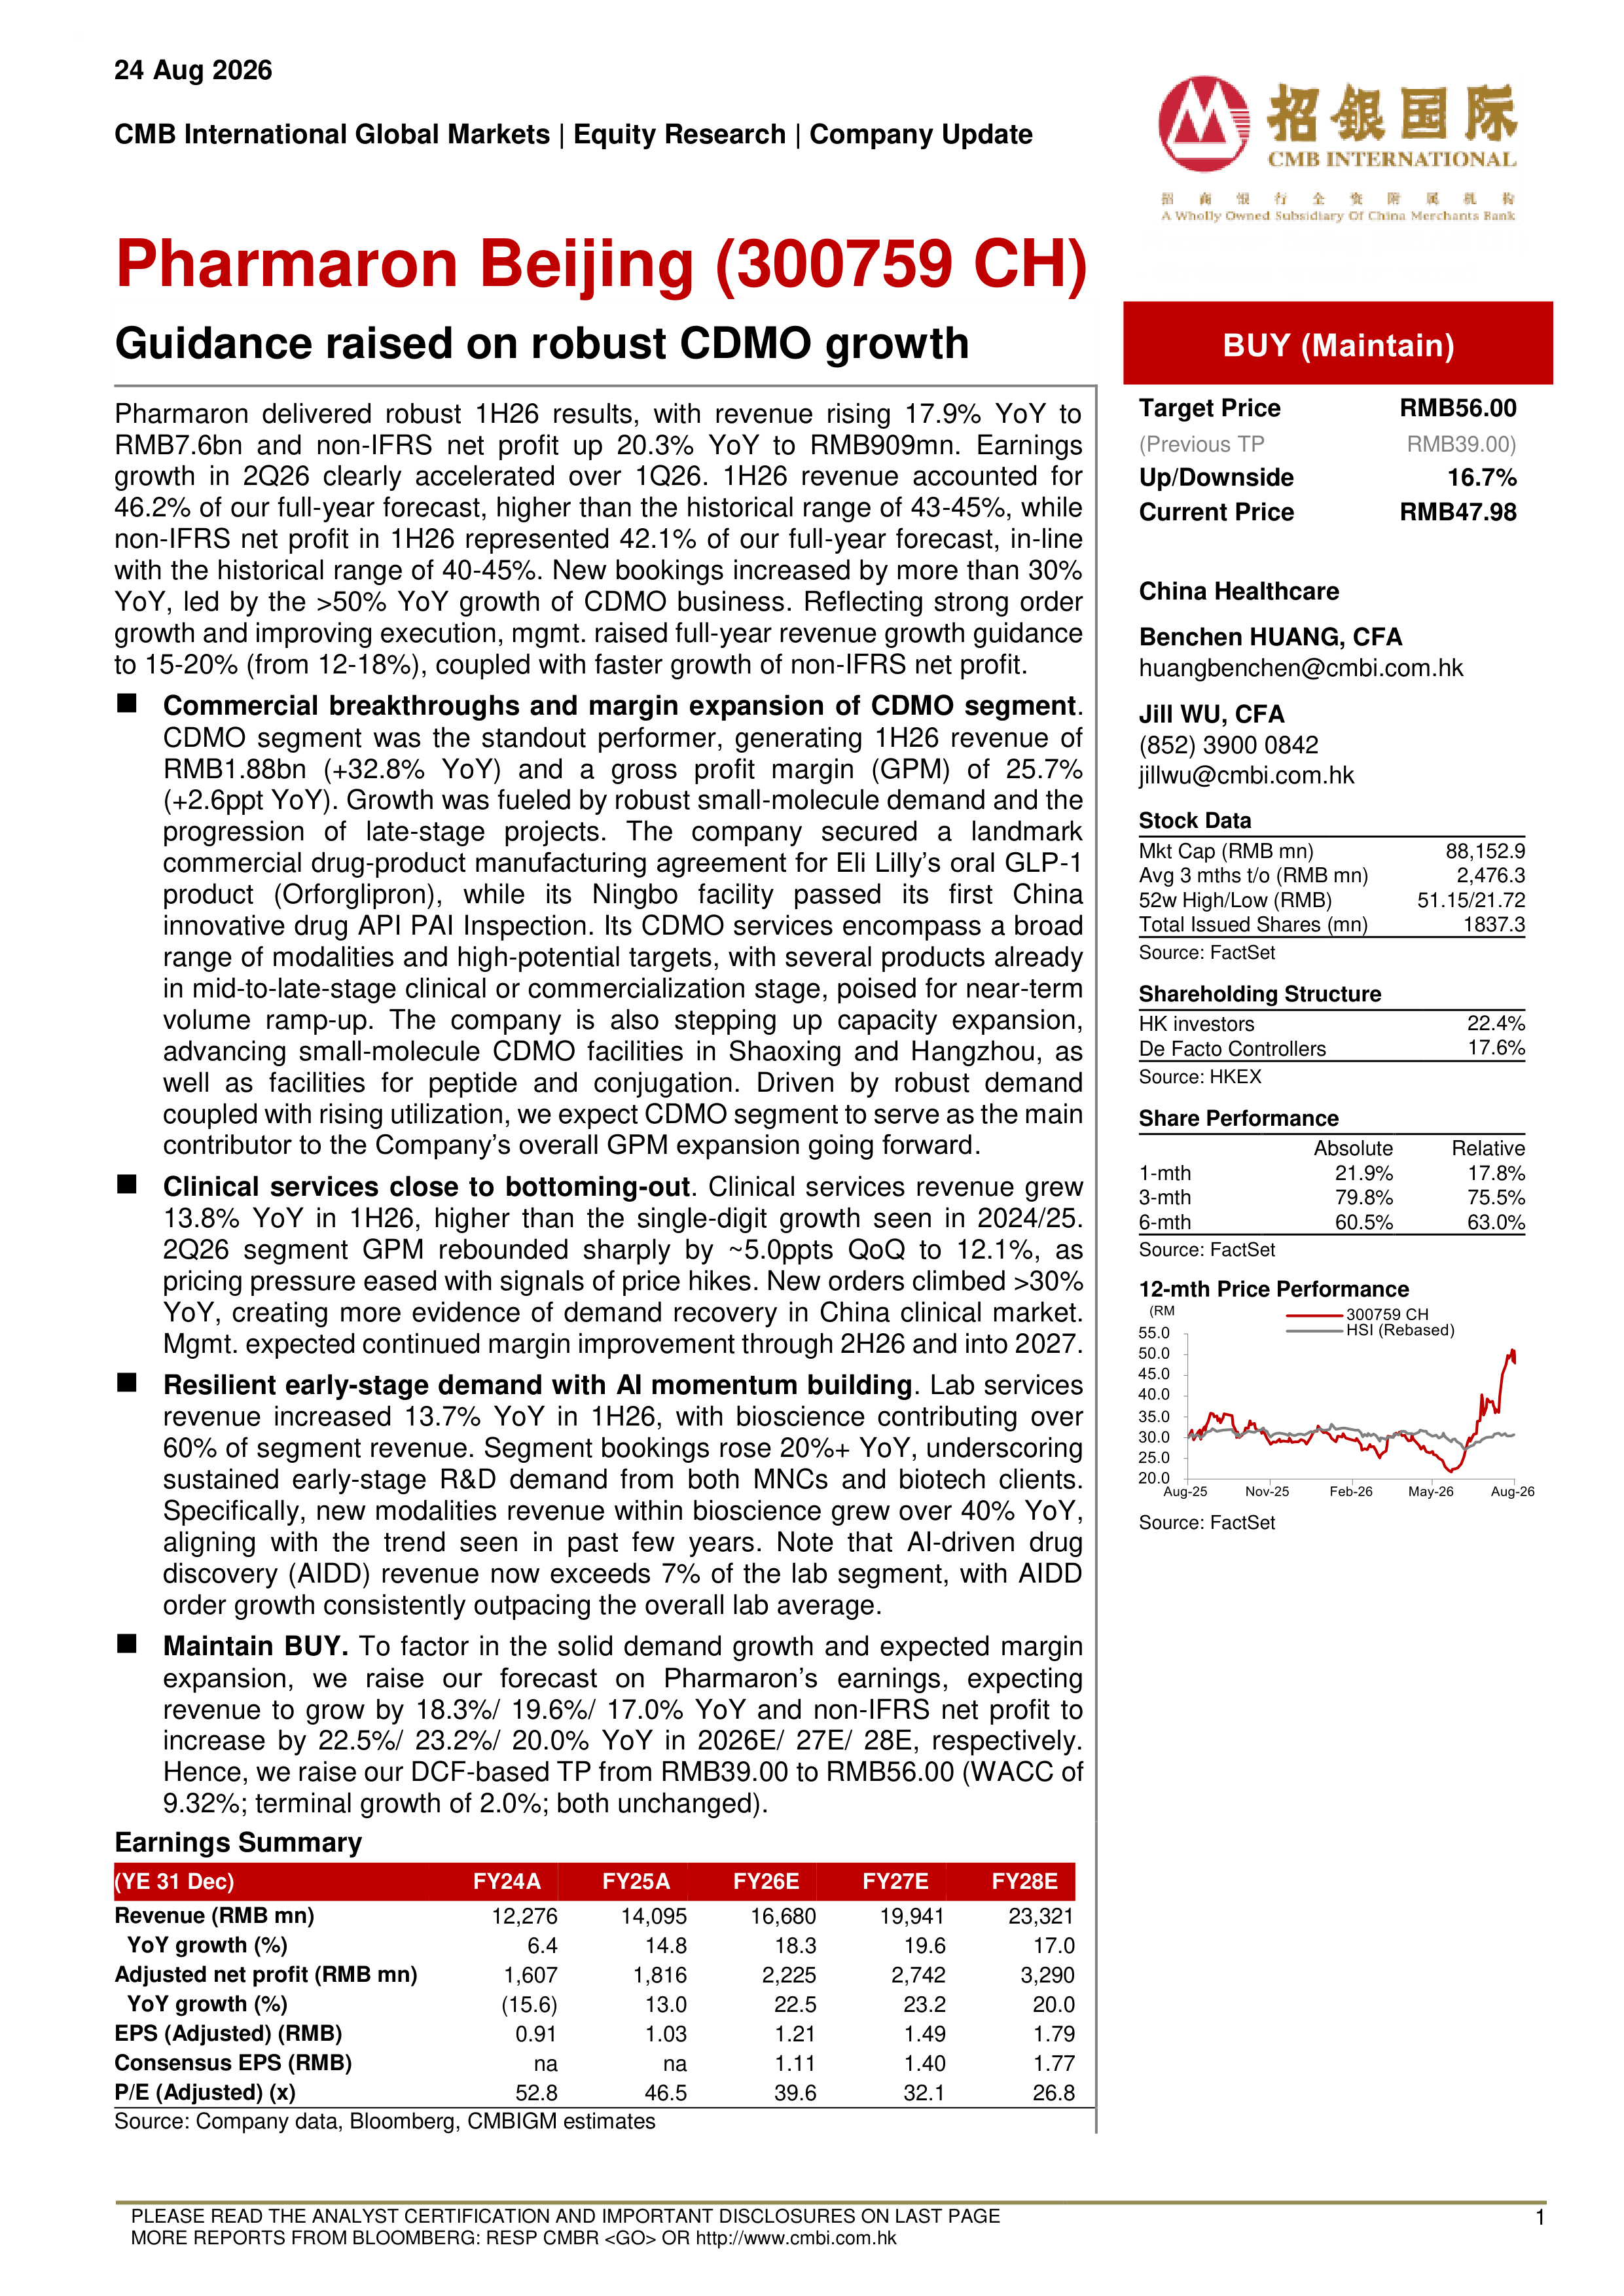
  康龙化成(300759)   Pharmaron delivered robust1H26results,with revenue rising17.9%YoY toRMB7.6bn and non-IFRS net profit up20.3%YoY to RMB909mn.Earningsgrowth in2Q26clearly accelerated over1Q26.1H26revenue accounted for46.2%of our full-year forecast,higher than the historical range of43-45%,whilenon-IFRS net profit in1H26represented42.1%of our full-year forecast,in-linewith the historical range of40-45%.New bookings increased by more than30%YoY,led by the>50%YoY growth of CDMO business.Reflecting strong ordergrowth and improving execution,mgmt.raised full-year revenue growth guidanceto15-20%(from12-18%),coupled with faster growth of non-IFRS net profit.   Commercial breakthroughs and margin expansion of CDMO segment.CDMO segment was the standout performer,generating1H26revenue ofRMB1.88bn(+32.8%YoY)and a gross profit margin(GPM)of25.7%(+2.6ppt YoY).Growth was fueled by robust small-molecule demand and theprogression of late-stage projects.The company secured a landmarkcommercial drug-product manufacturing agreement for Eli Lilly’s oral GLP-1product(Orforglipron),while its Ningbo facility passed its first Chinainnovative drug API PAI Inspection.Its CDMO services encompass a broadrange of modalities and high-potential targets,with several products alreadyin mid-to-late-stage clinical or commercialization stage,poised for near-termvolume ramp-up.The company is also stepping up capacity expansion,advancing small-molecule CDMO facilities in Shaoxing and Hangzhou,aswell as facilities for peptide and conjugation.Driven by robust demandcoupled with rising utilization,we expect CDMO segment to serve as the maincontributor to the Company’s overall GPM expansion going forward.   Clinical services close to bottoming-out.Clinical services revenue grew13.8%YoY in1H26,higher than the single-digit growth seen in2024/25.2Q26segment GPM rebounded sharply by~5.0ppts QoQ to12.1%,aspricing pressure eased with signals of price hikes.New orders climbed>30%YoY,creating more evidence of demand recovery in China clinical market.Mgmt.expected continued margin improvement through2H26and into2027.   Resilient early-stage demand with AI momentum building.Lab servicesrevenue increased13.7%YoY in1H26,with bioscience contributing over60%of segment revenue.Segment bookings rose20%+YoY,underscoringsustained early-stage R&D demand from both MNCs and biotech clients.Specifically,new modalities revenue within bioscience grew over40%YoY,aligning with the trend seen in past few years.Note that AI-driven drugdiscovery(AIDD)revenue now exceeds7%of the lab segment,with AIDDorder growth consistently outpacing the overall lab average.   Maintain BUY.To factor in the solid demand growth and expected marginexpansion,we raise our forecast on Pharmaron’s earnings,expectingrevenue to grow by18.3%/19.6%/17.0%YoY and non-IFRS net profit toincrease by22.5%/23.2%/20.0%YoY in2026E/27E/28E,respectively.Hence,we raise our DCF-based TP from RMB39.00to RMB56.00(WACC of9.32%;terminal growth of2.0%;both unchanged).   MORE REPORTS FROM BLOOMBERG:RESP CMBR<GO>OR http://www.cmbi.com.hk   Source:Company data,CMBIGM estimates   Source:Bloomberg,CMBIGM estimates   Risks:   1)Lower-than-expectedCDMO projects in the globalin early-stage R&D;3)geopolitical uncertainties.

报告专题:
  • 下载次数:

    2175 次

  • 发布机构:

    CMB International Capital Corporation Limited

  • 发布日期:

    2026-08-24

  • 页数:

    6页

下载全文
定制咨询
报告内容
报告摘要

  康龙化成(300759)

  Pharmaron delivered robust1H26results,with revenue rising17.9%YoY toRMB7.6bn and non-IFRS net profit up20.3%YoY to RMB909mn.Earningsgrowth in2Q26clearly accelerated over1Q26.1H26revenue accounted for46.2%of our full-year forecast,higher than the historical range of43-45%,whilenon-IFRS net profit in1H26represented42.1%of our full-year forecast,in-linewith the historical range of40-45%.New bookings increased by more than30%YoY,led by the>50%YoY growth of CDMO business.Reflecting strong ordergrowth and improving execution,mgmt.raised full-year revenue growth guidanceto15-20%(from12-18%),coupled with faster growth of non-IFRS net profit.

  Commercial breakthroughs and margin expansion of CDMO segment.CDMO segment was the standout performer,generating1H26revenue ofRMB1.88bn(+32.8%YoY)and a gross profit margin(GPM)of25.7%(+2.6ppt YoY).Growth was fueled by robust small-molecule demand and theprogression of late-stage projects.The company secured a landmarkcommercial drug-product manufacturing agreement for Eli Lilly’s oral GLP-1product(Orforglipron),while its Ningbo facility passed its first Chinainnovative drug API PAI Inspection.Its CDMO services encompass a broadrange of modalities and high-potential targets,with several products alreadyin mid-to-late-stage clinical or commercialization stage,poised for near-termvolume ramp-up.The company is also stepping up capacity expansion,advancing small-molecule CDMO facilities in Shaoxing and Hangzhou,aswell as facilities for peptide and conjugation.Driven by robust demandcoupled with rising utilization,we expect CDMO segment to serve as the maincontributor to the Company’s overall GPM expansion going forward.

  Clinical services close to bottoming-out.Clinical services revenue grew13.8%YoY in1H26,higher than the single-digit growth seen in2024/25.2Q26segment GPM rebounded sharply by~5.0ppts QoQ to12.1%,aspricing pressure eased with signals of price hikes.New orders climbed>30%YoY,creating more evidence of demand recovery in China clinical market.Mgmt.expected continued margin improvement through2H26and into2027.

  Resilient early-stage demand with AI momentum building.Lab servicesrevenue increased13.7%YoY in1H26,with bioscience contributing over60%of segment revenue.Segment bookings rose20%+YoY,underscoringsustained early-stage R&D demand from both MNCs and biotech clients.Specifically,new modalities revenue within bioscience grew over40%YoY,aligning with the trend seen in past few years.Note that AI-driven drugdiscovery(AIDD)revenue now exceeds7%of the lab segment,with AIDDorder growth consistently outpacing the overall lab average.

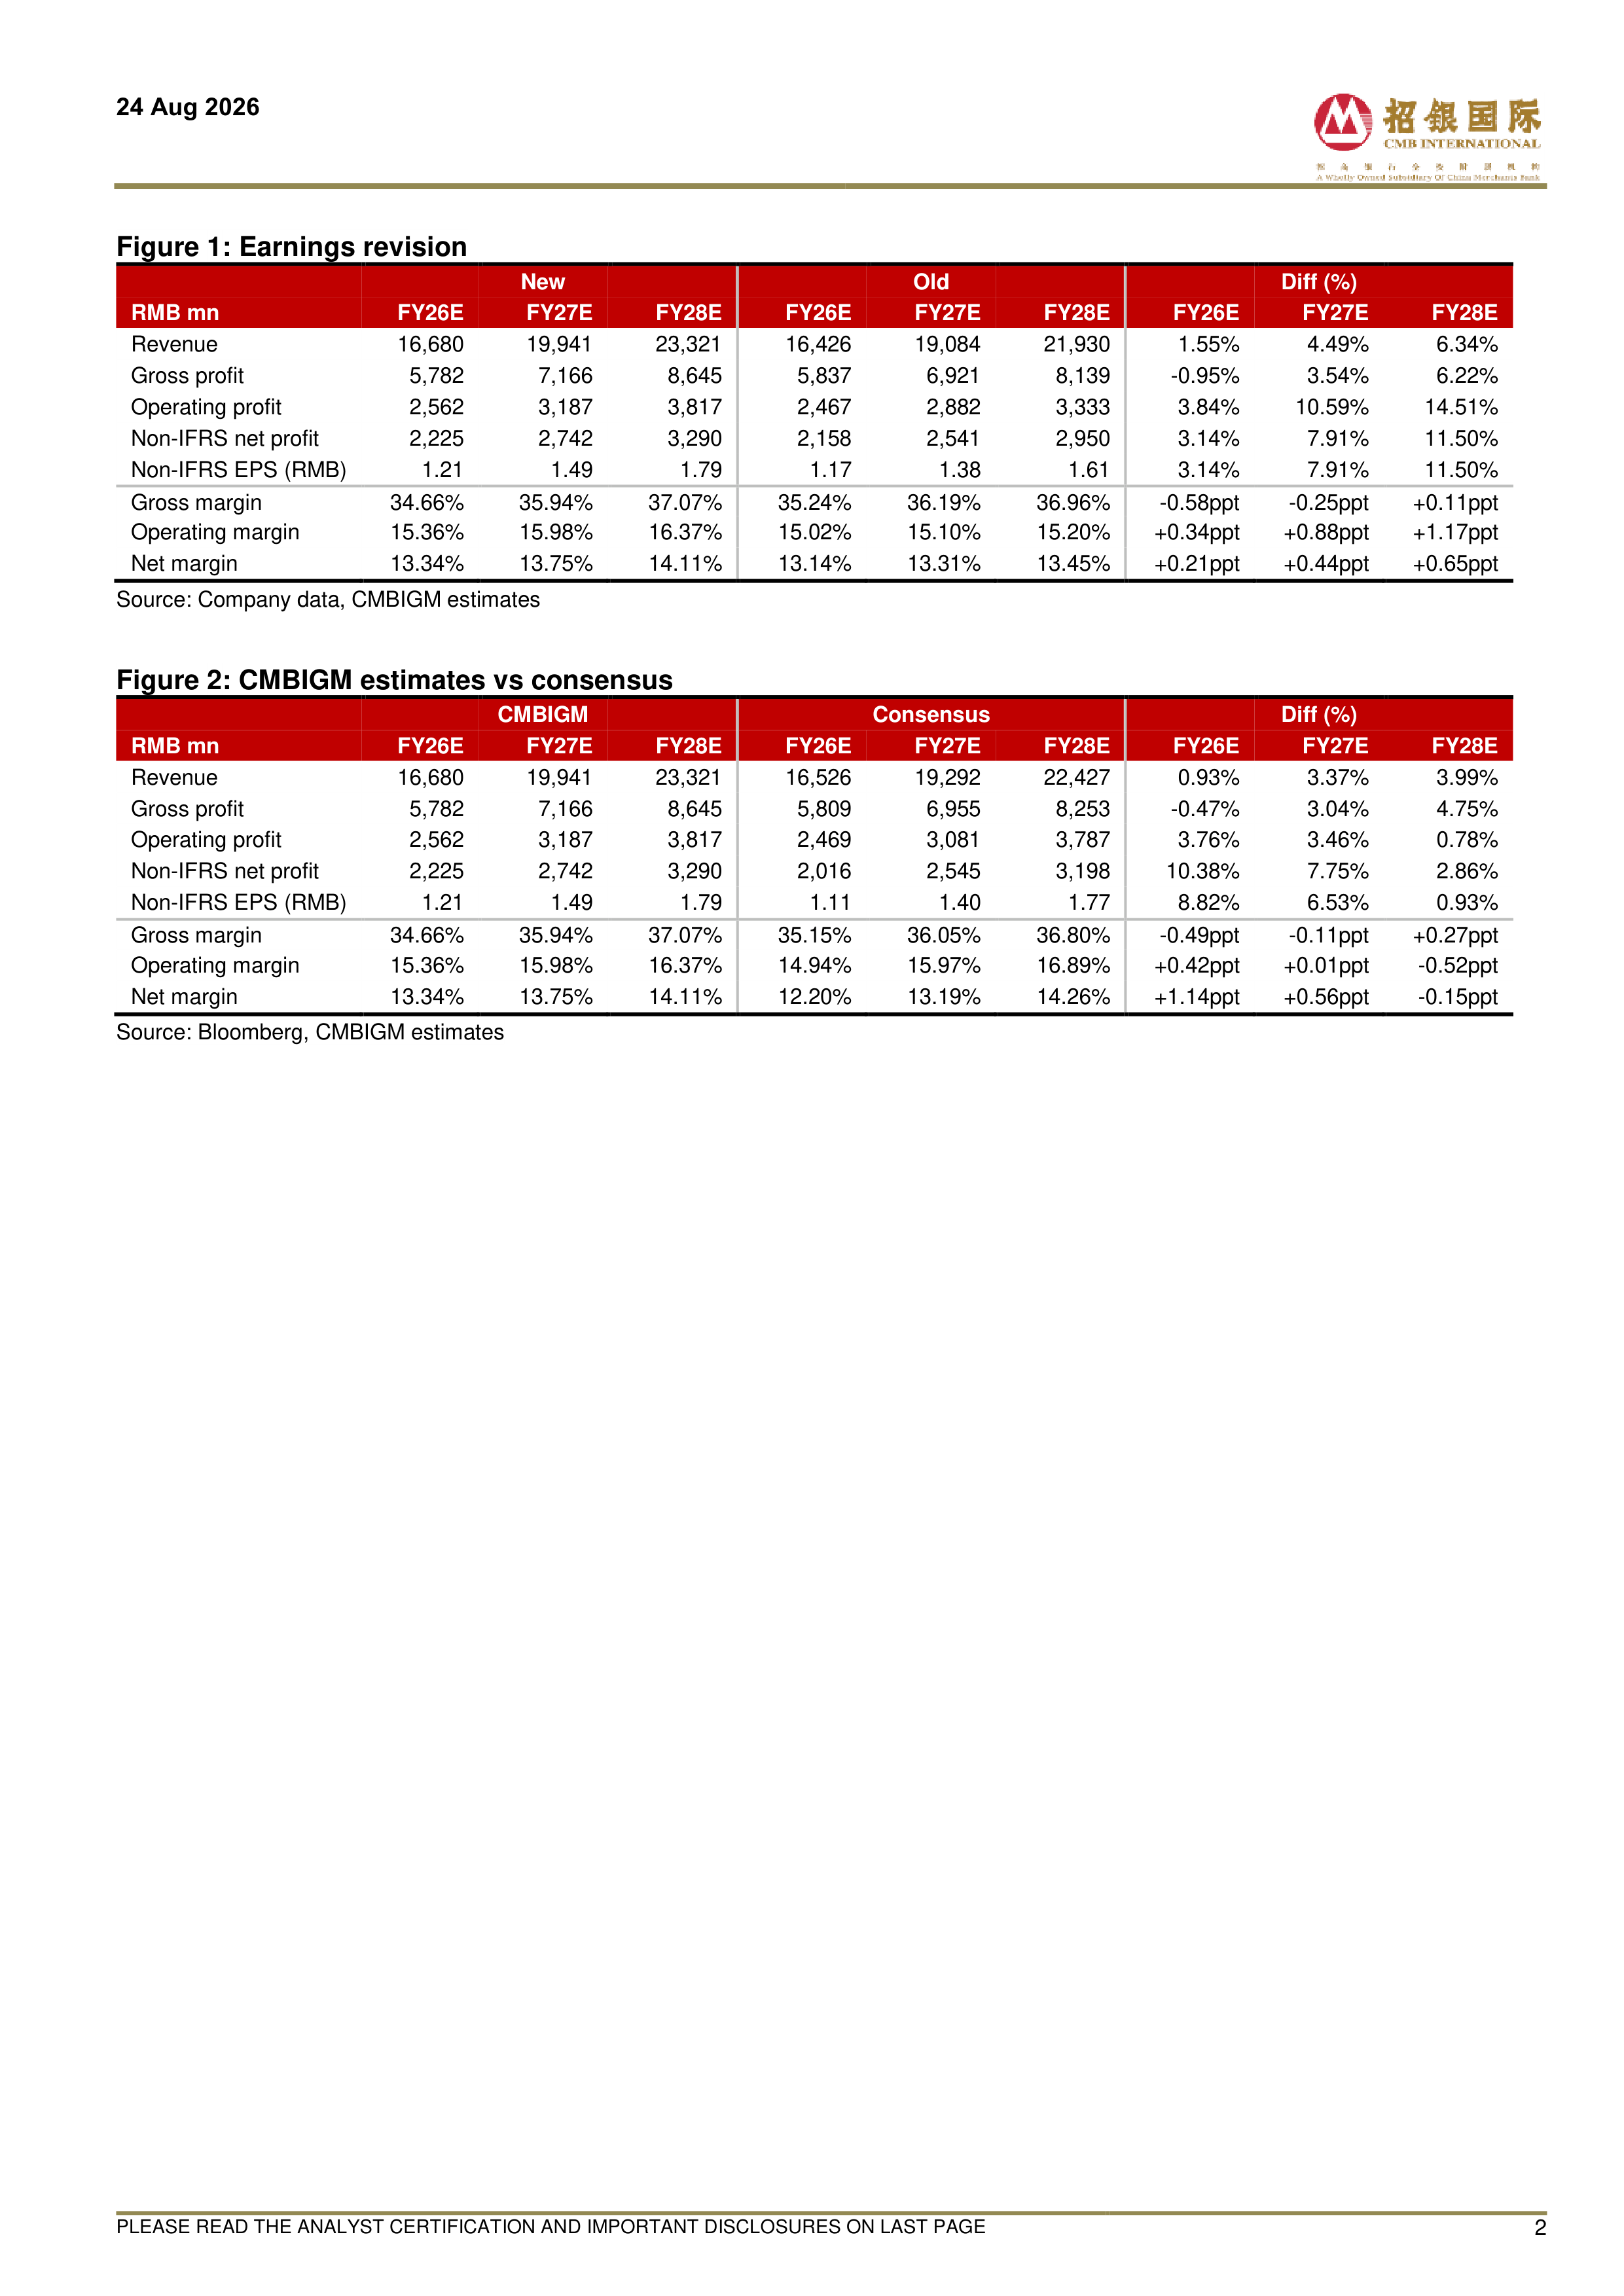
  Maintain BUY.To factor in the solid demand growth and expected marginexpansion,we raise our forecast on Pharmaron’s earnings,expectingrevenue to grow by18.3%/19.6%/17.0%YoY and non-IFRS net profit toincrease by22.5%/23.2%/20.0%YoY in2026E/27E/28E,respectively.Hence,we raise our DCF-based TP from RMB39.00to RMB56.00(WACC of9.32%;terminal growth of2.0%;both unchanged).

  MORE REPORTS FROM BLOOMBERG:RESP CMBR<GO>OR http://www.cmbi.com.hk

  Source:Company data,CMBIGM estimates

  Source:Bloomberg,CMBIGM estimates

  Risks:

  1)Lower-than-expectedCDMO projects in the globalin early-stage R&D;3)geopolitical uncertainties.

报告正文
摩熵医药企业版
9大数据库,200+子数据库,一站查询药品研发、临床、上市、销售、投资、政策等数据了解更多
我要试用
1 / 6
试读已结束,如需全文阅读可点击
下载全文
如果您有其他需求,请点击
定制服务咨询
CMB International Capital Corporation Limited最新报告
关于摩熵咨询

摩熵咨询是摩熵数科旗下生物医药专业咨询服务品牌,由深耕医药领域多年的专业人士组成,核心成员均来自国际顶级咨询机构和行业标杆企业,涵盖立项、市场、战略、投资等从业背景,依托摩熵数科丰富的外部专家资源及全面的医药全产业链数据库,为客户提供专业咨询服务和定制化解决方案

1W+
医药行业研究报告
200+
真实项目案例
1300+
业内高端专家资源
市场洞察与营销赋能
市场洞察与营销赋能
分析市场现状,洞察行业趋势,依托数据分析和深度研究,辅助商业决策。
立项评估及管线规划
立项评估及管线规划
提供疾病领域品种调研、专家访谈、品种立项、项目交易整套服务。
产业规划及研究服务
产业规划及研究服务
以数据为基础,为组织、园区、企业提供科学的决策依据和趋势线索。
多渠道数据分析及定制服务
多渠道数据分析及定制服务
帮助客户深入了解目标领域和市场情况,发现潜在机会,优化企业决策。
投资决策与交易估值
投资决策与交易估值
依托全球医药全产业链数据库与顶级投行级分析模型,为并购、融资、IPO提供全周期决策支持。
立即定制

标签云

洞察市场格局
解锁药品研发情报

400客服电话

  • 定制咨询业务

    400-9696-311 转2

  • 数据与AI定制业务

    400-9696-311 转3