2025中国医药研发创新与营销创新峰会
Robust overseas growth offset soft domestic demand

Robust overseas growth offset soft domestic demand

研报

Robust overseas growth offset soft domestic demand

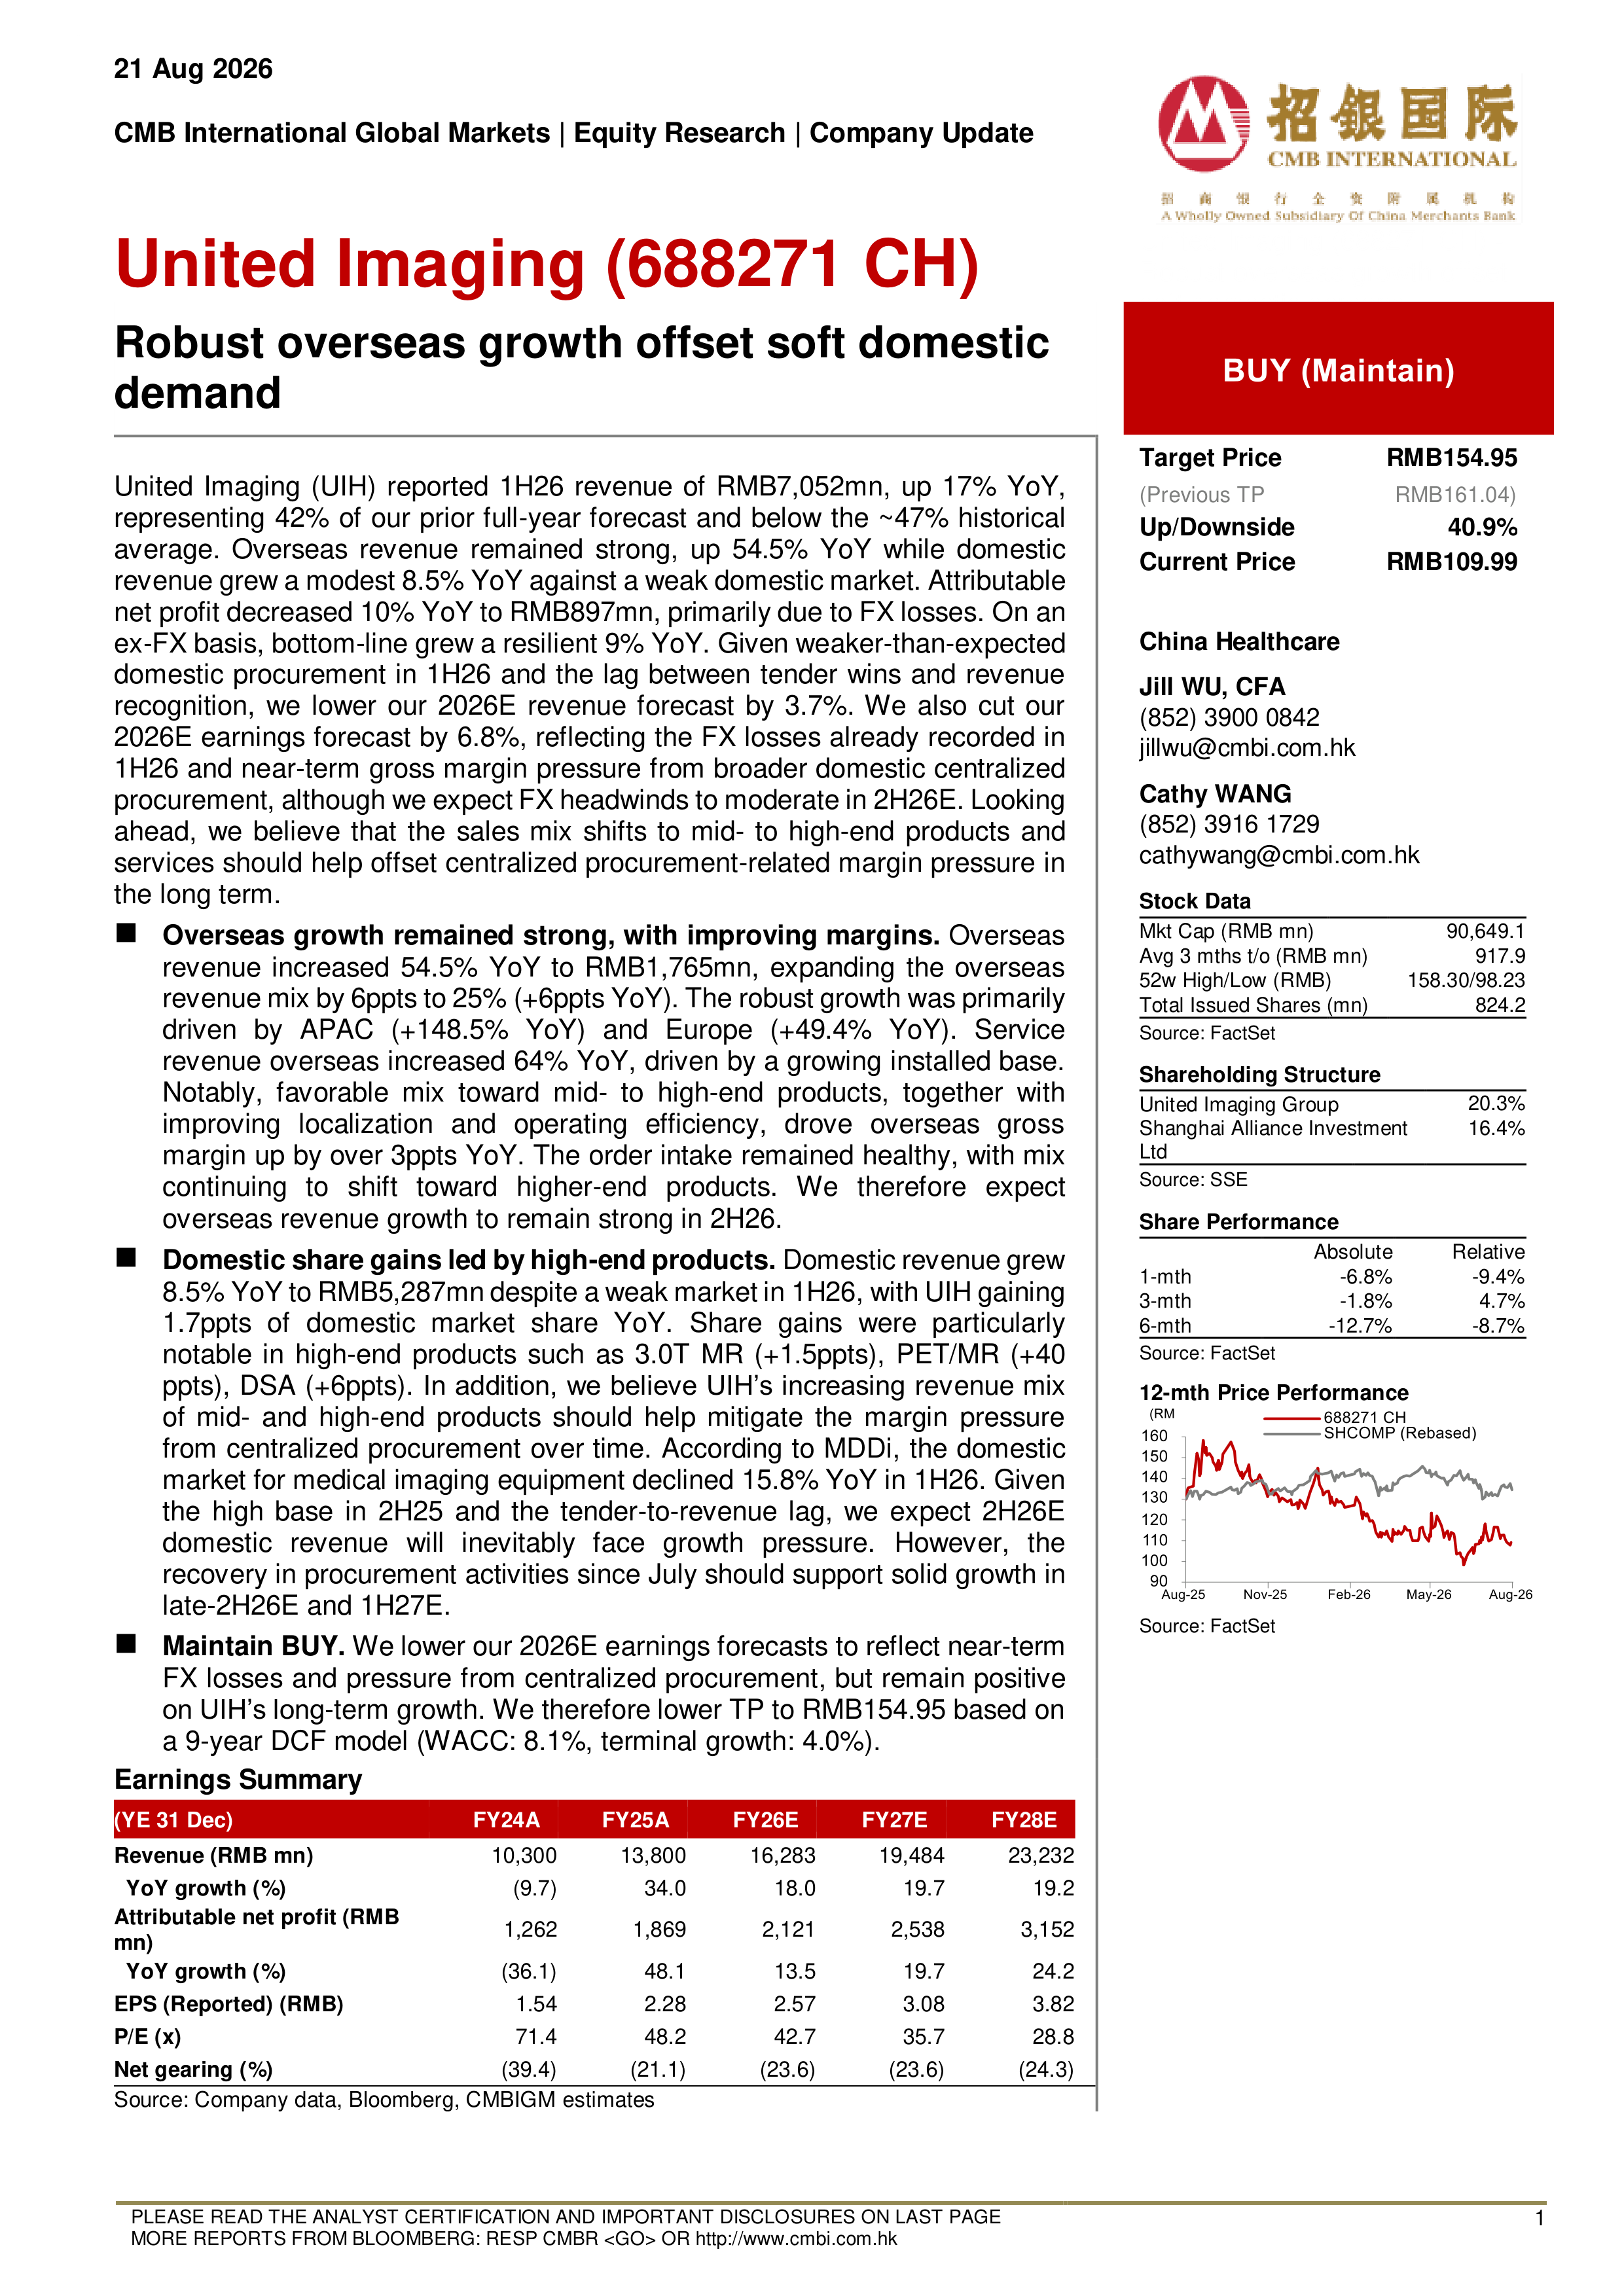
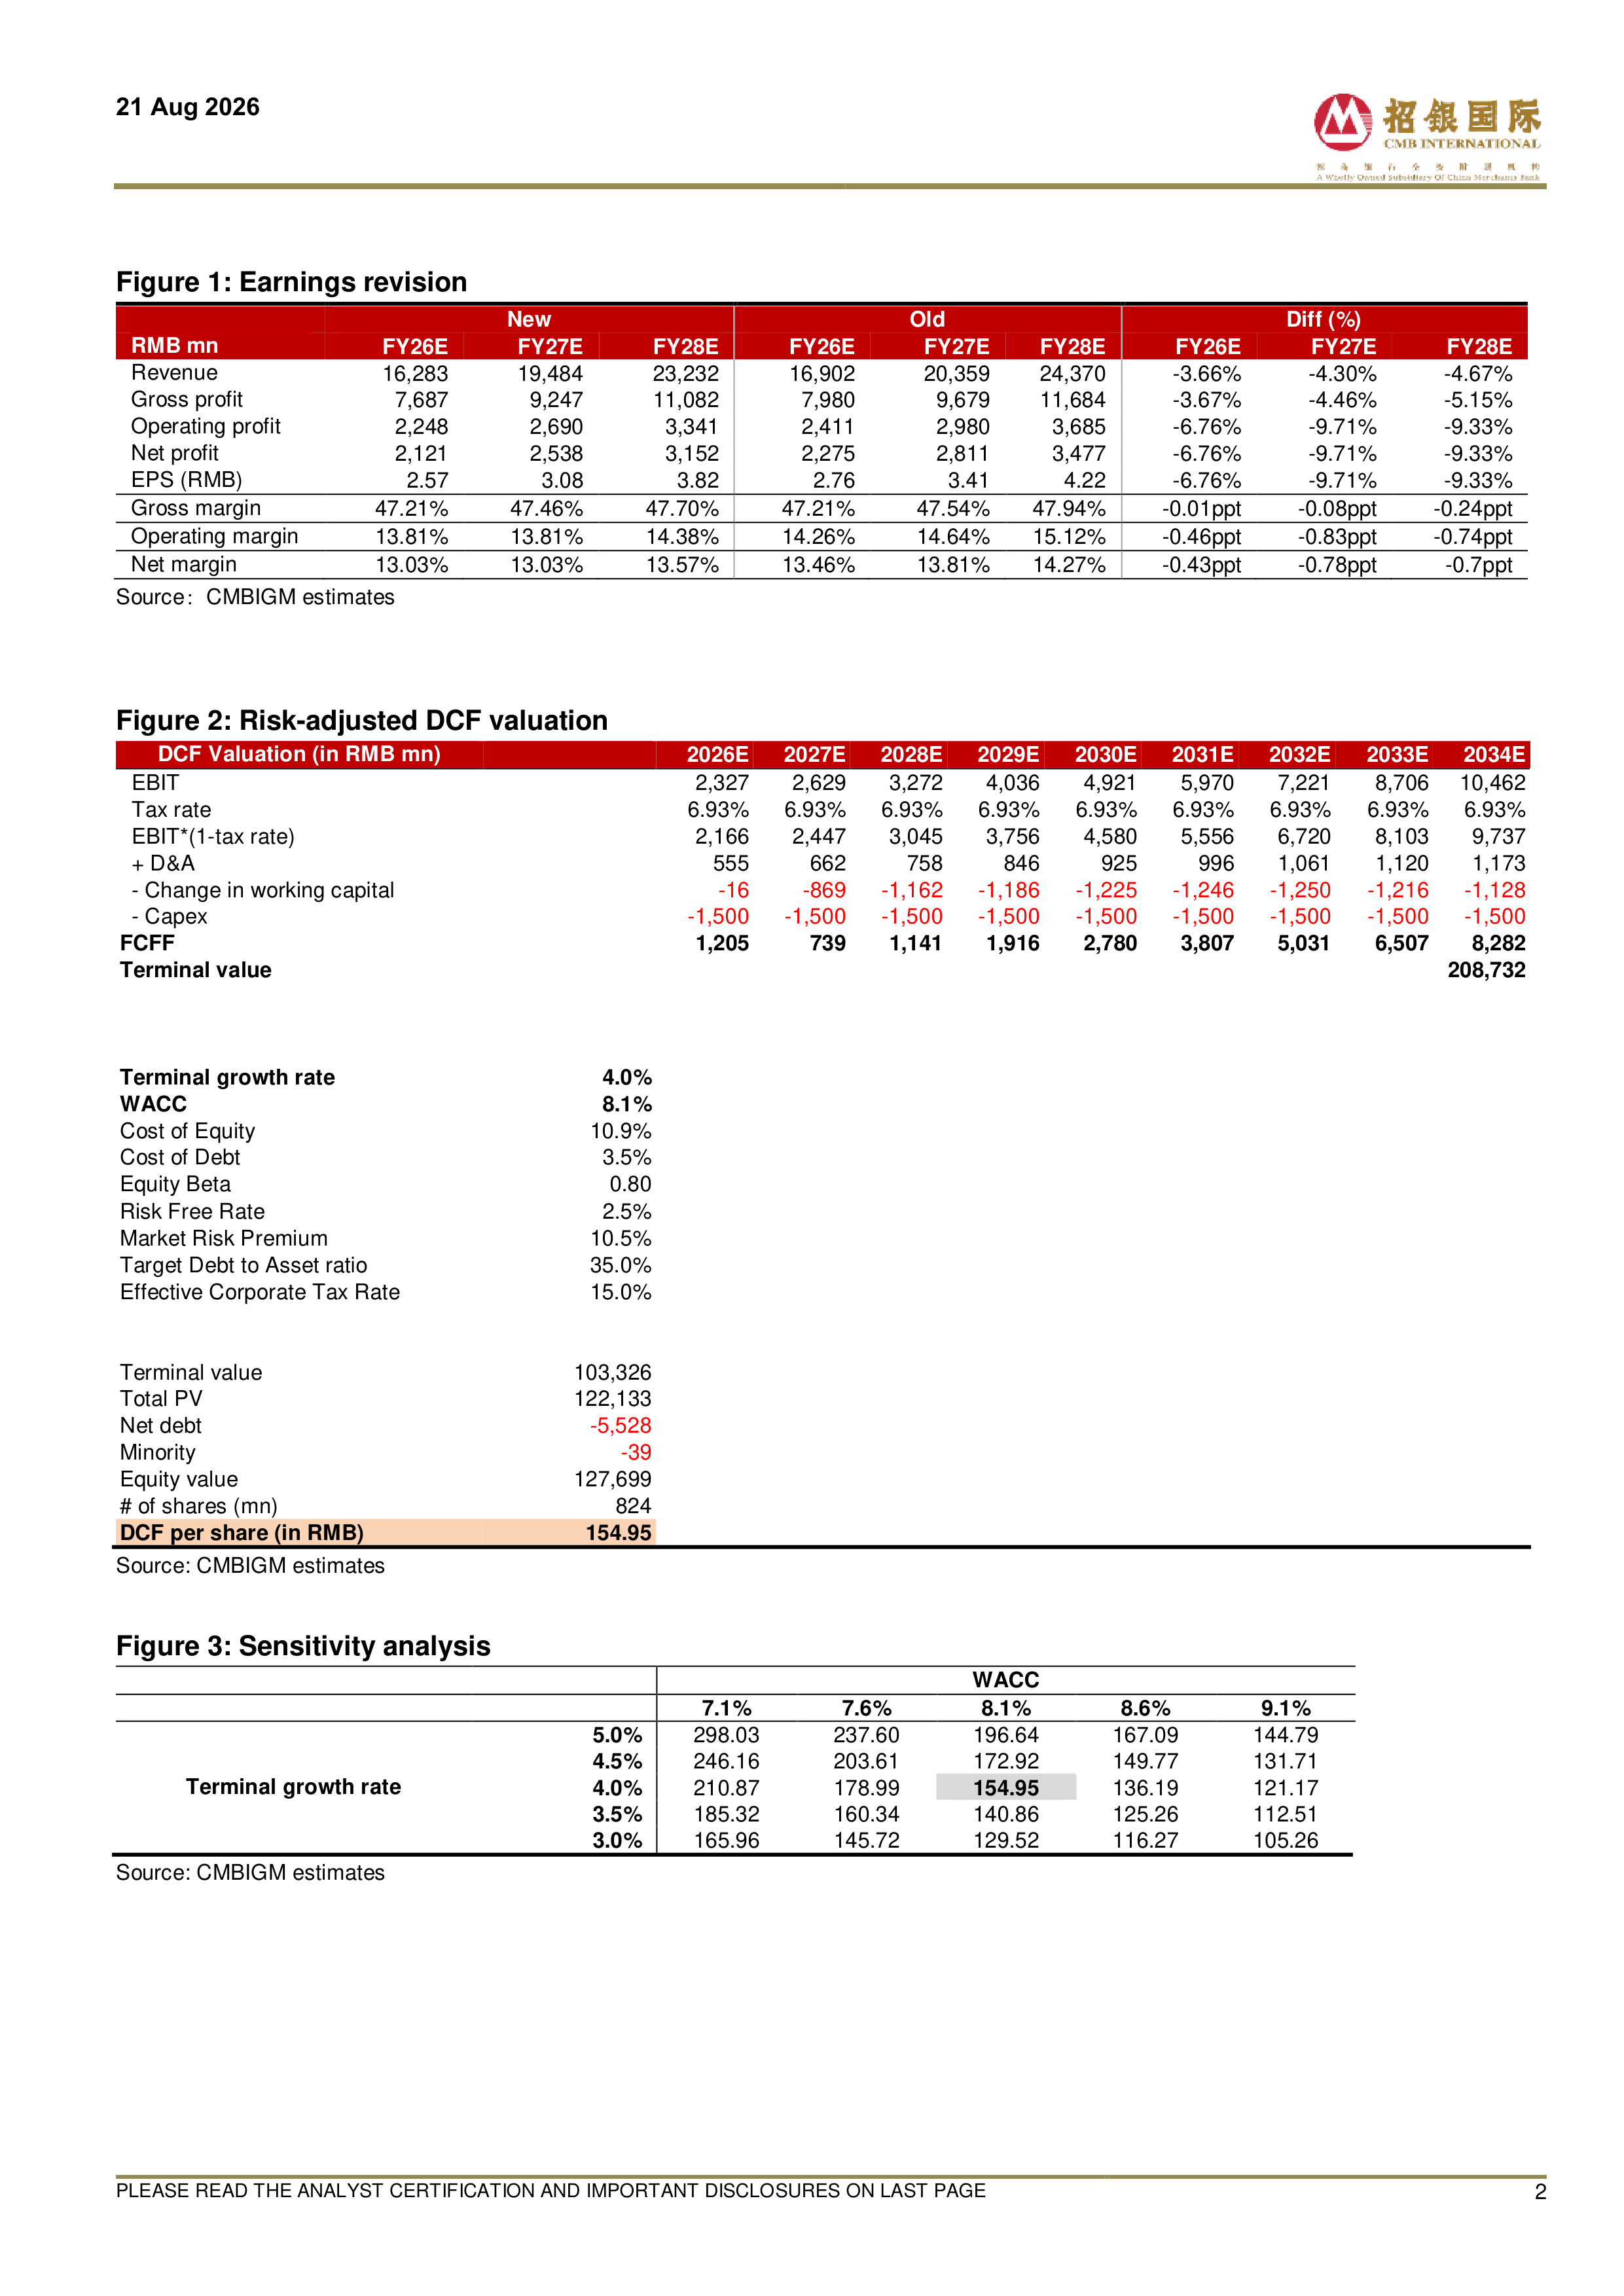
  联影医疗(688271)   United Imaging (UIH) reported 1H26 revenue of RMB7,052mn, up 17% YoY,representing 42% of our prior full-year forecast and below the ~47% historicalaverage. Overseas revenue remained strong, up 54.5% YoY while domesticrevenue grew a modest 8.5% YoY against a weak domestic market. Attributablenet profit decreased 10% YoY to RMB897mn, primarily due to FX losses. On anex-FX basis, bottom-line grew a resilient 9% YoY. Given weaker-than-expecteddomestic procurement in 1H26 and the lag between tender wins and revenuerecognition, we lower our 2026E revenue forecast by 3.7%. We also cut our2026E earnings forecast by 6.8%, reflecting the FX losses already recorded in1H26 and near-term gross margin pressure from broader domestic centralizedprocurement, although we expect FX headwinds to moderate in 2H26E. Lookingahead, we believe that the sales mix shifts to mid- to high-end products andservices should help offset centralized procurement-related margin pressure inthe long term.   Overseas growth remained strong, with improving margins. Overseasrevenue increased 54.5% YoY to RMB1,765mn, expanding the overseasrevenue mix by 6ppts to 25% (+6ppts YoY). The robust growth was primarilydriven by APAC (+148.5% YoY) and Europe (+49.4% YoY). Servicerevenue overseas increased 64% YoY, driven by a growing installed base.Notably, favorable mix toward mid- to high-end products, together withimproving localization and operating efficiency, drove overseas grossmargin up by over 3ppts YoY. The order intake remained healthy, with mixcontinuing to shift toward higher-end products. We therefore expectoverseas revenue growth to remain strong in 2H26.   Domestic share gains led by high-end products. Domestic revenue grew8.5% YoY to RMB5,287mn despite a weak market in 1H26, with UIH gaining1.7ppts of domestic market share YoY. Share gains were particularlynotable in high-end products such as 3.0T MR (+1.5ppts), PET/MR (+40ppts), DSA (+6ppts). In addition, we believe UIH’s increasing revenue mixof mid- and high-end products should help mitigate the margin pressurefrom centralized procurement over time. According to MDDi, the domesticmarket for medical imaging equipment declined 15.8% YoY in 1H26. Giventhe high base in 2H25 and the tender-to-revenue lag, we expect 2H26Edomestic revenue will inevitably face growth pressure. However, therecovery in procurement activities since July should support solid growth inlate-2H26E and 1H27E.   Maintain BUY. We lower our 2026E earnings forecasts to reflect near-termFX losses and pressure from centralized procurement, but remain positiveon UIH’s long-term growth. We therefore lower TP to RMB154.95 based ona 9-year DCF model (WACC: 8.1%, terminal growth: 4.0%).

报告专题:
  • 下载次数:

    2281 次

  • 发布机构:

    CMB International Capital Corporation Limited

  • 发布日期:

    2026-08-21

  • 页数:

    6页

下载全文
定制咨询
报告内容
报告摘要

  联影医疗(688271)

  United Imaging (UIH) reported 1H26 revenue of RMB7,052mn, up 17% YoY,representing 42% of our prior full-year forecast and below the ~47% historicalaverage. Overseas revenue remained strong, up 54.5% YoY while domesticrevenue grew a modest 8.5% YoY against a weak domestic market. Attributablenet profit decreased 10% YoY to RMB897mn, primarily due to FX losses. On anex-FX basis, bottom-line grew a resilient 9% YoY. Given weaker-than-expecteddomestic procurement in 1H26 and the lag between tender wins and revenuerecognition, we lower our 2026E revenue forecast by 3.7%. We also cut our2026E earnings forecast by 6.8%, reflecting the FX losses already recorded in1H26 and near-term gross margin pressure from broader domestic centralizedprocurement, although we expect FX headwinds to moderate in 2H26E. Lookingahead, we believe that the sales mix shifts to mid- to high-end products andservices should help offset centralized procurement-related margin pressure inthe long term.

  Overseas growth remained strong, with improving margins. Overseasrevenue increased 54.5% YoY to RMB1,765mn, expanding the overseasrevenue mix by 6ppts to 25% (+6ppts YoY). The robust growth was primarilydriven by APAC (+148.5% YoY) and Europe (+49.4% YoY). Servicerevenue overseas increased 64% YoY, driven by a growing installed base.Notably, favorable mix toward mid- to high-end products, together withimproving localization and operating efficiency, drove overseas grossmargin up by over 3ppts YoY. The order intake remained healthy, with mixcontinuing to shift toward higher-end products. We therefore expectoverseas revenue growth to remain strong in 2H26.

  Domestic share gains led by high-end products. Domestic revenue grew8.5% YoY to RMB5,287mn despite a weak market in 1H26, with UIH gaining1.7ppts of domestic market share YoY. Share gains were particularlynotable in high-end products such as 3.0T MR (+1.5ppts), PET/MR (+40ppts), DSA (+6ppts). In addition, we believe UIH’s increasing revenue mixof mid- and high-end products should help mitigate the margin pressurefrom centralized procurement over time. According to MDDi, the domesticmarket for medical imaging equipment declined 15.8% YoY in 1H26. Giventhe high base in 2H25 and the tender-to-revenue lag, we expect 2H26Edomestic revenue will inevitably face growth pressure. However, therecovery in procurement activities since July should support solid growth inlate-2H26E and 1H27E.

  Maintain BUY. We lower our 2026E earnings forecasts to reflect near-termFX losses and pressure from centralized procurement, but remain positiveon UIH’s long-term growth. We therefore lower TP to RMB154.95 based ona 9-year DCF model (WACC: 8.1%, terminal growth: 4.0%).


报告正文
摩熵医药企业版
9大数据库,200+子数据库,一站查询药品研发、临床、上市、销售、投资、政策等数据了解更多
我要试用
1 / 6
试读已结束,如需全文阅读可点击
下载全文
如果您有其他需求,请点击
定制服务咨询
CMB International Capital Corporation Limited最新报告
关于摩熵咨询

摩熵咨询是摩熵数科旗下生物医药专业咨询服务品牌,由深耕医药领域多年的专业人士组成,核心成员均来自国际顶级咨询机构和行业标杆企业,涵盖立项、市场、战略、投资等从业背景,依托摩熵数科丰富的外部专家资源及全面的医药全产业链数据库,为客户提供专业咨询服务和定制化解决方案

1W+
医药行业研究报告
200+
真实项目案例
1300+
业内高端专家资源
市场洞察与营销赋能
市场洞察与营销赋能
分析市场现状,洞察行业趋势,依托数据分析和深度研究,辅助商业决策。
立项评估及管线规划
立项评估及管线规划
提供疾病领域品种调研、专家访谈、品种立项、项目交易整套服务。
产业规划及研究服务
产业规划及研究服务
以数据为基础,为组织、园区、企业提供科学的决策依据和趋势线索。
多渠道数据分析及定制服务
多渠道数据分析及定制服务
帮助客户深入了解目标领域和市场情况,发现潜在机会,优化企业决策。
投资决策与交易估值
投资决策与交易估值
依托全球医药全产业链数据库与顶级投行级分析模型,为并购、融资、IPO提供全周期决策支持。
立即定制

标签云

洞察市场格局
解锁药品研发情报

400客服电话

  • 定制咨询业务

    400-9696-311 转2

  • 数据与AI定制业务

    400-9696-311 转3