2025中国医药研发创新与营销创新峰会
Guidance raised after exceptional 2Q26 earnings

Guidance raised after exceptional 2Q26 earnings

研报

Guidance raised after exceptional 2Q26 earnings

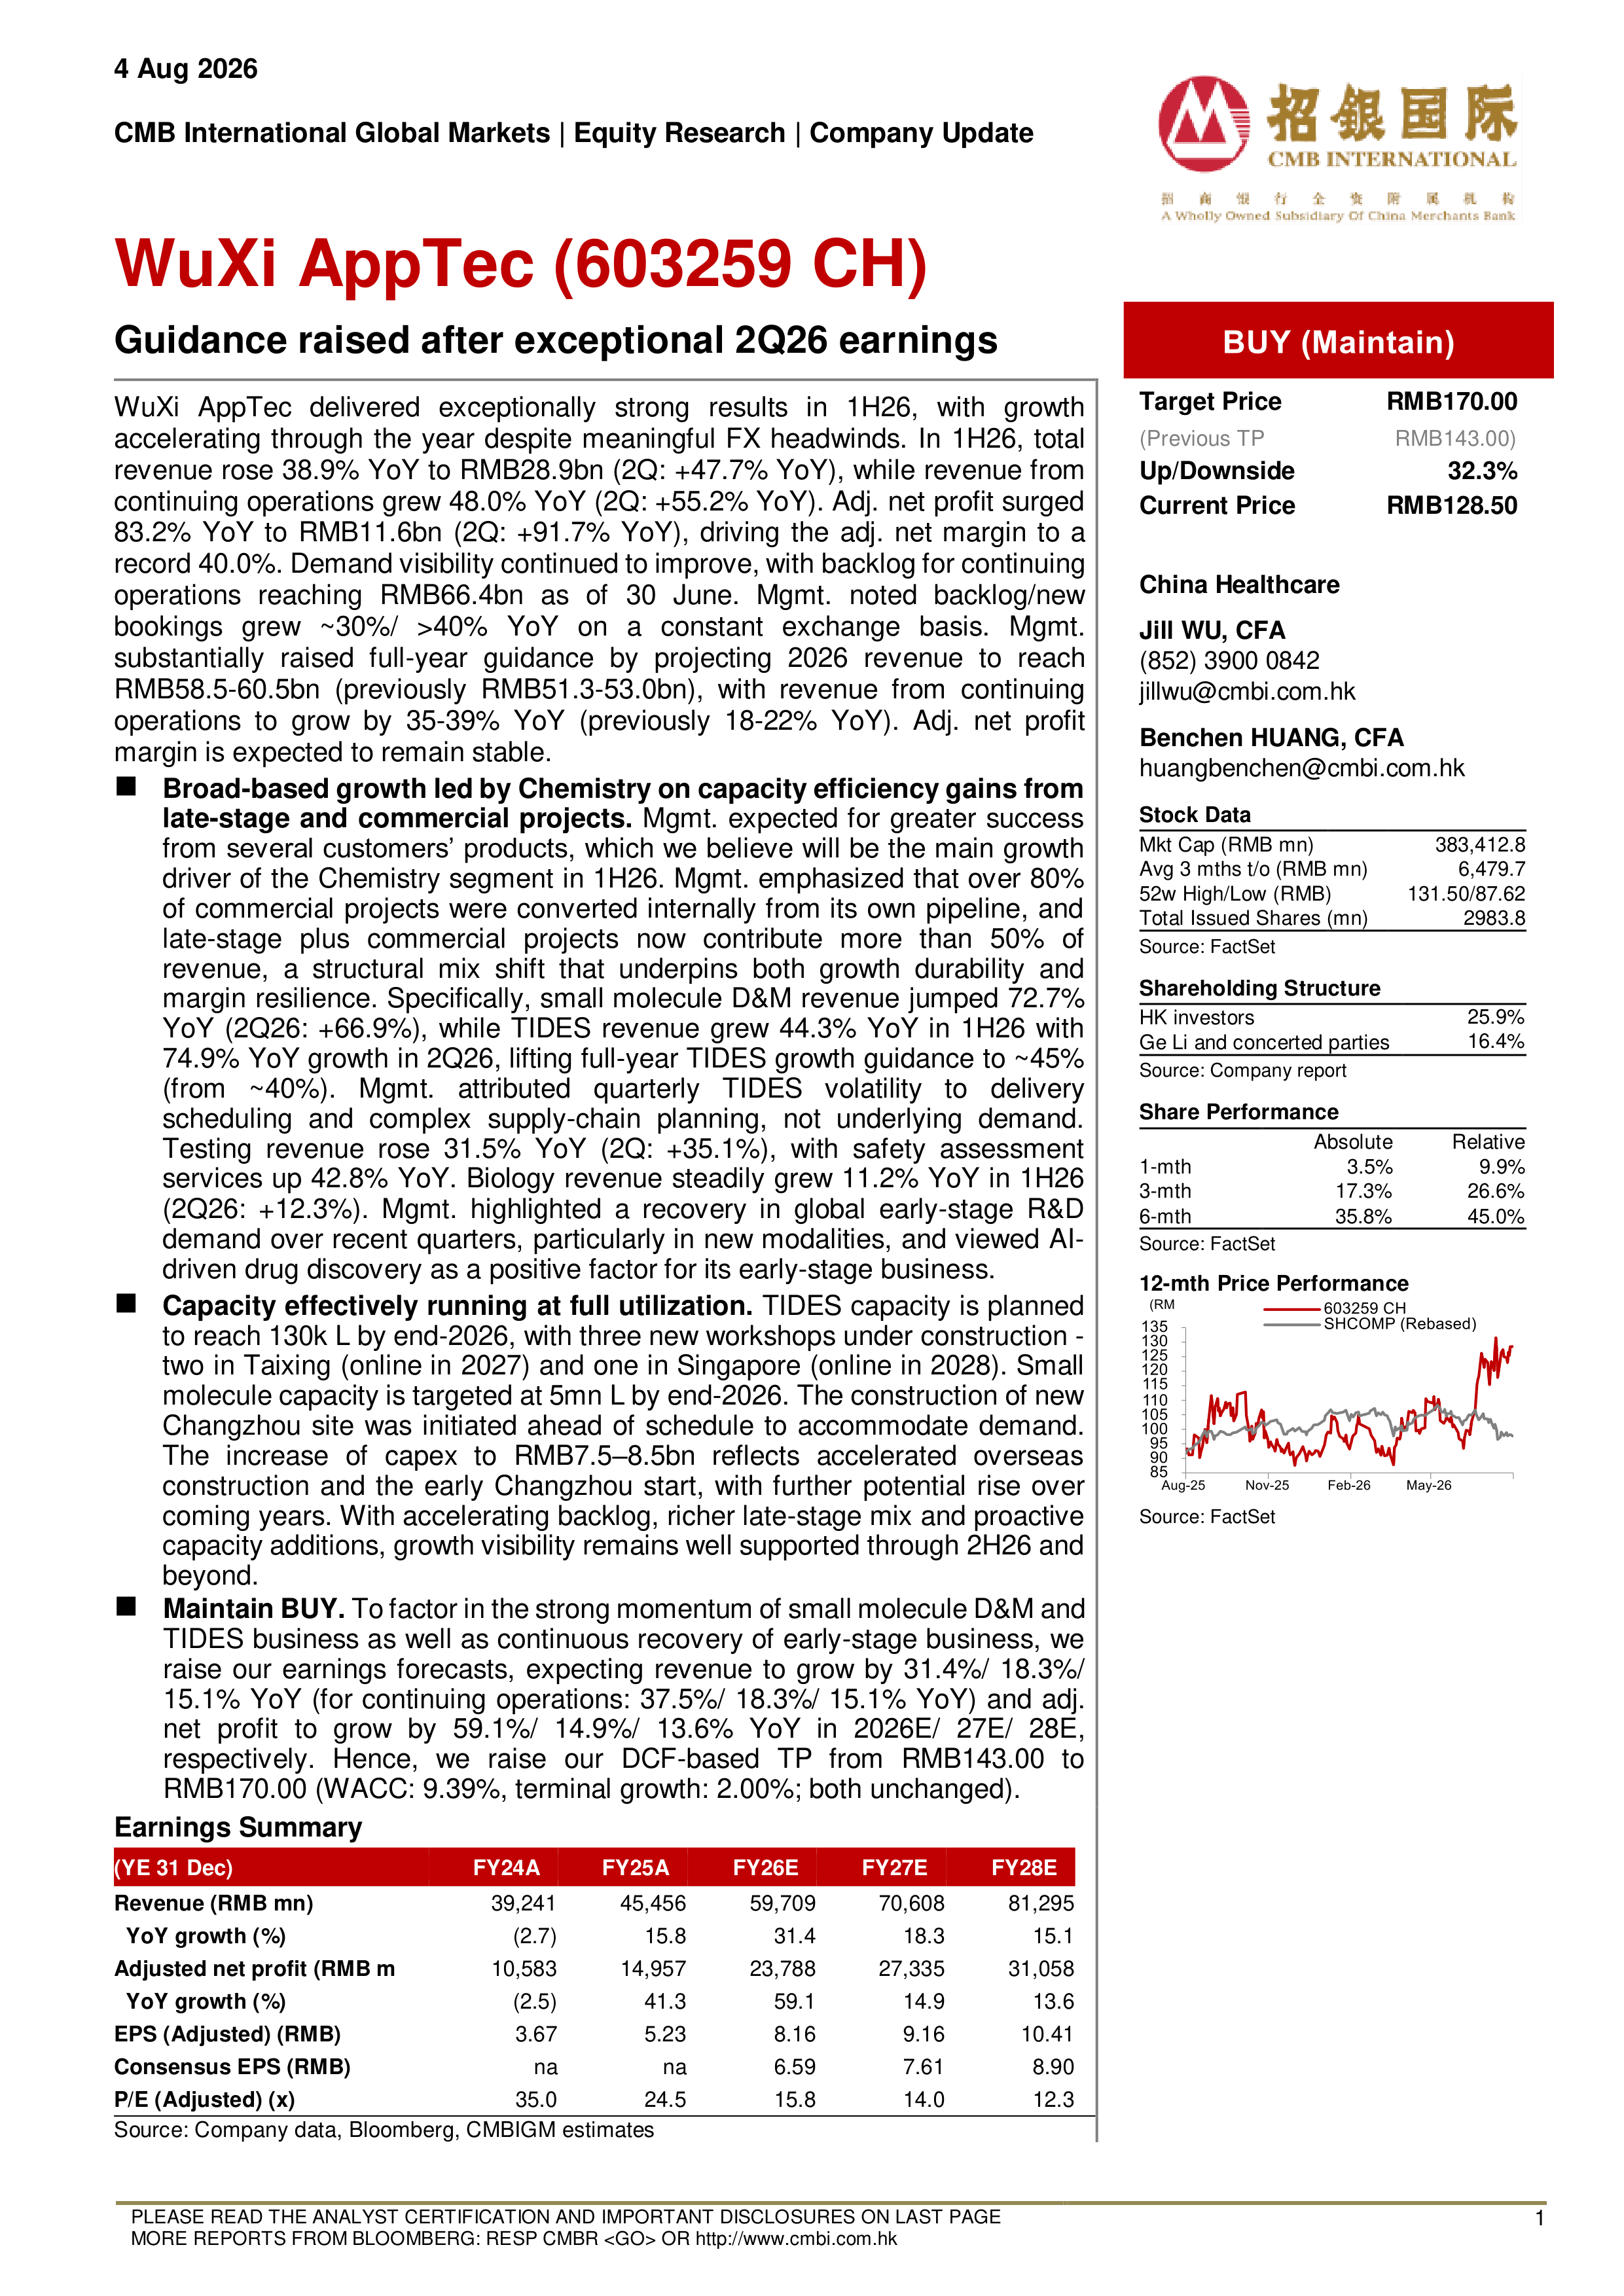
  药明康德(603259)   WuXi AppTec delivered exceptionally strong results in 1H26, with growthaccelerating through the year despite meaningful FX headwinds. In 1H26, totalrevenue rose 38.9% YoY to RMB28.9bn (2Q: +47.7% YoY), while revenue fromcontinuing operations grew 48.0% YoY (2Q: +55.2% YoY). Adj. net profit surged83.2% YoY to RMB11.6bn (2Q: +91.7% YoY), driving the adj. net margin to arecord 40.0%. Demand visibility continued to improve, with backlog for continuingoperations reaching RMB66.4bn as of 30 June. Mgmt. noted backlog/newbookings grew ~30%/ >40% YoY on a constant exchange basis. Mgmt.substantially raised full-year guidance by projecting 2026 revenue to reachRMB58.5-60.5bn (previously RMB51.3-53.0bn), with revenue from continuingoperations to grow by 35-39% YoY (previously 18-22% YoY). Adj. net profitmargin is expected to remain stable.   Broad-based growth led by Chemistry on capacity efficiency gains fromlate-stage and commercial projects. Mgmt. expected for greater successfrom several customers’ products, which we believe will be the main growthdriver of the Chemistry segment in 1H26. Mgmt. emphasized that over 80%of commercial projects were converted internally from its own pipeline, andlate-stage plus commercial projects now contribute more than 50% ofrevenue, a structural mix shift that underpins both growth durability andmargin resilience. Specifically, small molecule D&M revenue jumped 72.7%YoY (2Q26: +66.9%), while TIDES revenue grew 44.3% YoY in 1H26 with74.9% YoY growth in 2Q26, lifting full-year TIDES growth guidance to ~45%(from ~40%). Mgmt. attributed quarterly TIDES volatility to deliveryscheduling and complex supply-chain planning, not underlying demand.Testing revenue rose 31.5% YoY (2Q: +35.1%), with safety assessmentservices up 42.8% YoY. Biology revenue steadily grew 11.2% YoY in 1H26(2Q26: +12.3%). Mgmt. highlighted a recovery in global early-stage R&Ddemand over recent quarters, particularly in new modalities, and viewed AIdriven drug discovery as a positive factor for its early-stage business.   Capacity effectively running at full utilization. TIDES capacity is plannedto reach 130k L by end-2026, with three new workshops under construction -two in Taixing (online in 2027) and one in Singapore (online in 2028). Smallmolecule capacity is targeted at 5mn L by end-2026. The construction of newChangzhou site was initiated ahead of schedule to accommodate demand.The increase of capex to RMB7.5–8.5bn reflects accelerated overseasconstruction and the early Changzhou start, with further potential rise overcoming years. With accelerating backlog, richer late-stage mix and proactivecapacity additions, growth visibility remains well supported through 2H26 andbeyond.   Maintain BUY. To factor in the strong momentum of small molecule D&M andTIDES business as well as continuous recovery of early-stage business, weraise our earnings forecasts, expecting revenue to grow by 31.4%/ 18.3%/15.1% YoY (for continuing operations: 37.5%/ 18.3%/ 15.1% YoY) and adj.net profit to grow by 59.1%/ 14.9%/ 13.6% YoY in 2026E/ 27E/ 28E,respectively. Hence, we raise our DCF-based TP from RMB143.00 toRMB170.00 (WACC: 9.39%, terminal growth: 2.00%; both unchanged).

报告专题:
  • 下载次数:

    2988 次

  • 发布机构:

    CMB International Capital Corporation Limited

  • 发布日期:

    2026-08-04

  • 页数:

    6页

下载全文
定制咨询
报告内容
报告摘要

  药明康德(603259)

  WuXi AppTec delivered exceptionally strong results in 1H26, with growthaccelerating through the year despite meaningful FX headwinds. In 1H26, totalrevenue rose 38.9% YoY to RMB28.9bn (2Q: +47.7% YoY), while revenue fromcontinuing operations grew 48.0% YoY (2Q: +55.2% YoY). Adj. net profit surged83.2% YoY to RMB11.6bn (2Q: +91.7% YoY), driving the adj. net margin to arecord 40.0%. Demand visibility continued to improve, with backlog for continuingoperations reaching RMB66.4bn as of 30 June. Mgmt. noted backlog/newbookings grew ~30%/ >40% YoY on a constant exchange basis. Mgmt.substantially raised full-year guidance by projecting 2026 revenue to reachRMB58.5-60.5bn (previously RMB51.3-53.0bn), with revenue from continuingoperations to grow by 35-39% YoY (previously 18-22% YoY). Adj. net profitmargin is expected to remain stable.

  Broad-based growth led by Chemistry on capacity efficiency gains fromlate-stage and commercial projects. Mgmt. expected for greater successfrom several customers’ products, which we believe will be the main growthdriver of the Chemistry segment in 1H26. Mgmt. emphasized that over 80%of commercial projects were converted internally from its own pipeline, andlate-stage plus commercial projects now contribute more than 50% ofrevenue, a structural mix shift that underpins both growth durability andmargin resilience. Specifically, small molecule D&M revenue jumped 72.7%YoY (2Q26: +66.9%), while TIDES revenue grew 44.3% YoY in 1H26 with74.9% YoY growth in 2Q26, lifting full-year TIDES growth guidance to ~45%(from ~40%). Mgmt. attributed quarterly TIDES volatility to deliveryscheduling and complex supply-chain planning, not underlying demand.Testing revenue rose 31.5% YoY (2Q: +35.1%), with safety assessmentservices up 42.8% YoY. Biology revenue steadily grew 11.2% YoY in 1H26(2Q26: +12.3%). Mgmt. highlighted a recovery in global early-stage R&Ddemand over recent quarters, particularly in new modalities, and viewed AIdriven drug discovery as a positive factor for its early-stage business.

  Capacity effectively running at full utilization. TIDES capacity is plannedto reach 130k L by end-2026, with three new workshops under construction -two in Taixing (online in 2027) and one in Singapore (online in 2028). Smallmolecule capacity is targeted at 5mn L by end-2026. The construction of newChangzhou site was initiated ahead of schedule to accommodate demand.The increase of capex to RMB7.5–8.5bn reflects accelerated overseasconstruction and the early Changzhou start, with further potential rise overcoming years. With accelerating backlog, richer late-stage mix and proactivecapacity additions, growth visibility remains well supported through 2H26 andbeyond.

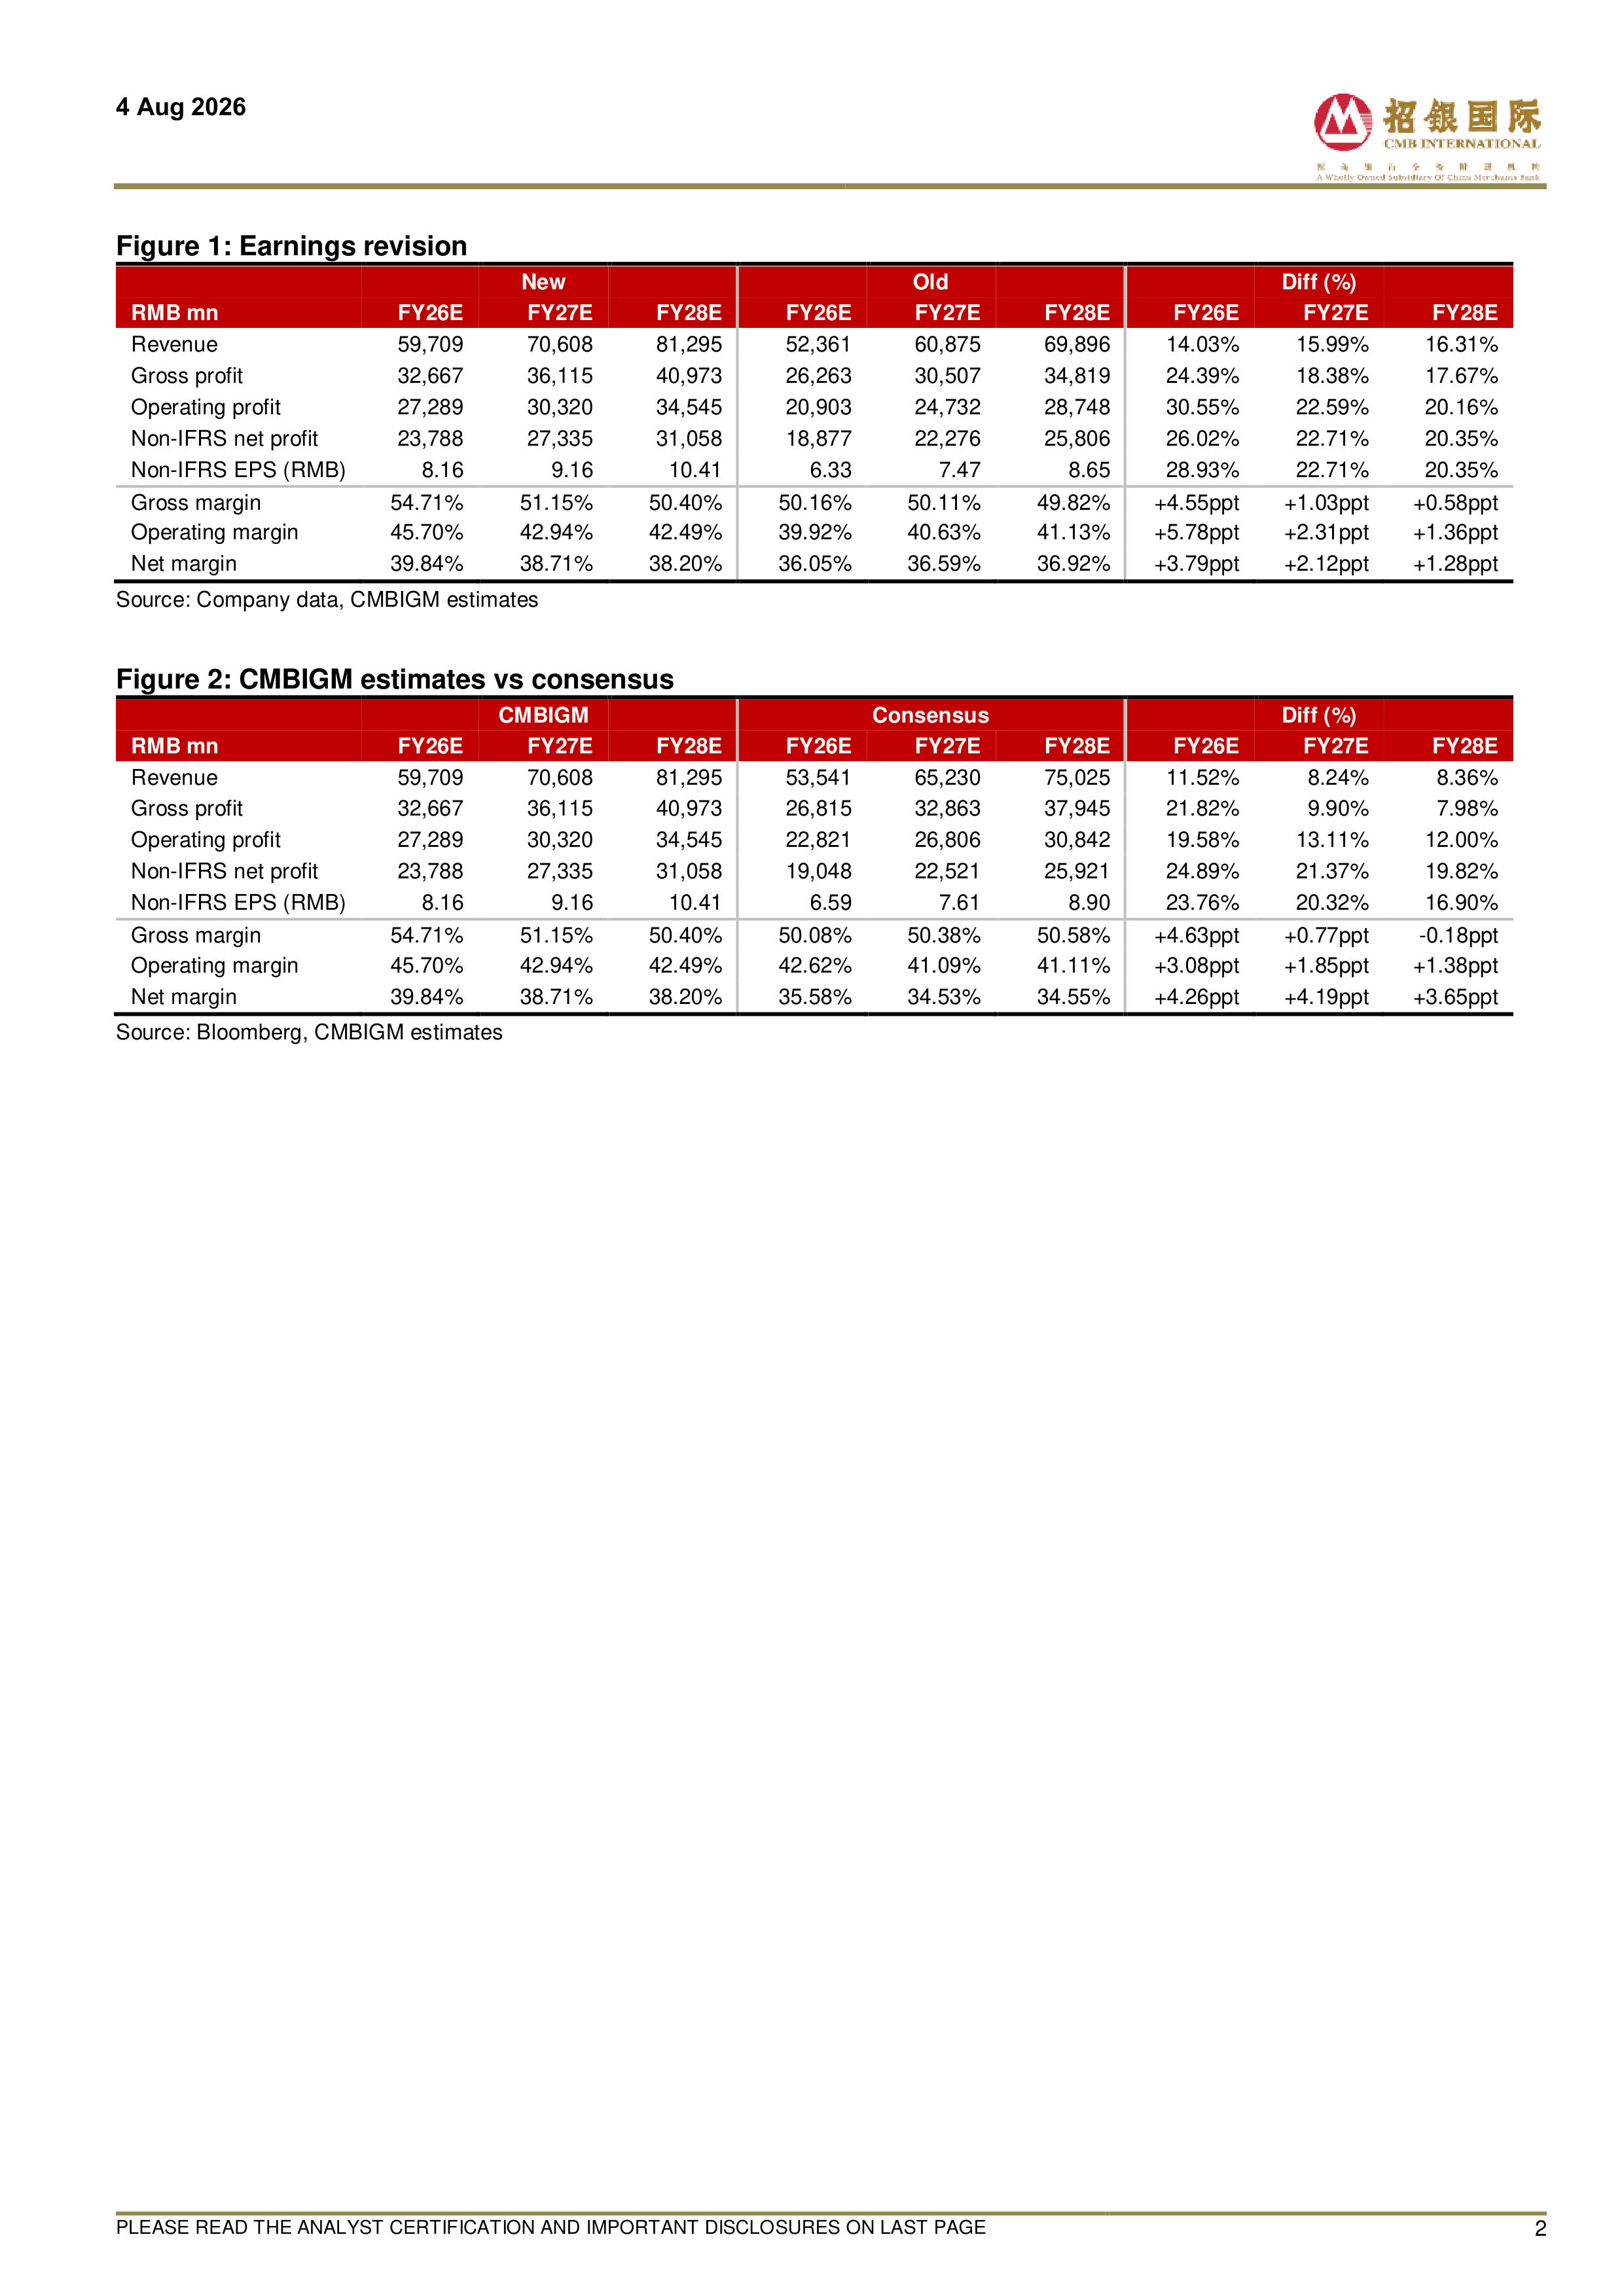
  Maintain BUY. To factor in the strong momentum of small molecule D&M andTIDES business as well as continuous recovery of early-stage business, weraise our earnings forecasts, expecting revenue to grow by 31.4%/ 18.3%/15.1% YoY (for continuing operations: 37.5%/ 18.3%/ 15.1% YoY) and adj.net profit to grow by 59.1%/ 14.9%/ 13.6% YoY in 2026E/ 27E/ 28E,respectively. Hence, we raise our DCF-based TP from RMB143.00 toRMB170.00 (WACC: 9.39%, terminal growth: 2.00%; both unchanged).


报告正文
摩熵医药企业版
9大数据库,200+子数据库,一站查询药品研发、临床、上市、销售、投资、政策等数据了解更多
我要试用
1 / 6
试读已结束,如需全文阅读可点击
下载全文
如果您有其他需求,请点击
定制服务咨询
CMB International Capital Corporation Limited最新报告
关于摩熵咨询

摩熵咨询是摩熵数科旗下生物医药专业咨询服务品牌,由深耕医药领域多年的专业人士组成,核心成员均来自国际顶级咨询机构和行业标杆企业,涵盖立项、市场、战略、投资等从业背景,依托摩熵数科丰富的外部专家资源及全面的医药全产业链数据库,为客户提供专业咨询服务和定制化解决方案

1W+
医药行业研究报告
200+
真实项目案例
1300+
业内高端专家资源
市场洞察与营销赋能
市场洞察与营销赋能
分析市场现状,洞察行业趋势,依托数据分析和深度研究,辅助商业决策。
立项评估及管线规划
立项评估及管线规划
提供疾病领域品种调研、专家访谈、品种立项、项目交易整套服务。
产业规划及研究服务
产业规划及研究服务
以数据为基础,为组织、园区、企业提供科学的决策依据和趋势线索。
多渠道数据分析及定制服务
多渠道数据分析及定制服务
帮助客户深入了解目标领域和市场情况,发现潜在机会,优化企业决策。
投资决策与交易估值
投资决策与交易估值
依托全球医药全产业链数据库与顶级投行级分析模型,为并购、融资、IPO提供全周期决策支持。
立即定制

标签云

洞察市场格局
解锁药品研发情报

400客服电话

  • 定制咨询业务

    400-9696-311 转2

  • 数据与AI定制业务

    400-9696-311 转3